A Practical Guide to Evaluating the Best Rated Mortgage Brokers in Your Market
Core Criteria for Evaluating the Best Rated Mortgage Brokers
Finding the right loan professional means looking past flashy advertisements and sales pitches. When you search for the best rated mortgage brokers, a strong rating should reflect consistent execution, deep local market knowledge, and clear communication throughout the loan process. Whether you are browsing directory listings for local Tampa mortgage professionals or researching local mortgage brokers near me, specific standards separate seasoned loan advisors from average transactional originators.
Evaluating mortgage professionals in Florida involves understanding regional nuances. From flood zone determinations along coastal Pinellas communities to local property tax assessments in Hillsborough County, working with someone who understands our local market dynamics can save you unexpected setbacks during escrow. Florida real estate often presents unique considerations, including wind mitigation reports, four-point inspections for older properties, and specific condominium reserve requirements that out-of-market lenders frequently misunderstand.
Transparent Licensing, Regulatory Credentials, and Experience
Proper licensing provides your baseline consumer protection. A reputable mortgage broker should readily provide their individual and company National Multimarket Licensing System (NMLS) credentials. Borrowers can verify licensing history, employment records, and past regulatory actions through the publicly accessible NMLS Consumer Access registry.
Beyond basic compliance and Equal Housing Lender standards, extensive transaction experience matters substantially. Real estate cycles bring changing guidelines and tighter credit overlays. Working with an originator who has managed hundreds of closed transactions means they have successfully resolved complex title issues, unique property appraisals along Tampa Bay waterways, and unexpected underwriting conditions.
Key licensing and background criteria to review include:
- Active state licensing in Florida without disciplinary actions on public record.
- Verifiable transaction track record demonstrating experience across diverse real estate environments.
- Clear commitment to consumer compliance, fair lending practices, and transparent document presentation.
- Demonstrated familiarity with regional real estate contracts and local closing timelines across Florida counties.
Multi-Lender Access and Diverse Loan Options
A retail bank loan officer offers only the products in their single institution's product menu. If your debt-to-income ratio, property type, or employment structure falls outside their specific parameters, your application can stall out entirely. Independent mortgage brokers operate on a different model. By working with extensive wholesale networks and portfolio lenders, an independent broker shops across multiple institutions to match you with suitable financing structures.
Having access to a broad wholesale lending network allows you to explore options such as:
- Conventional financing for primary residences, second homes, and investment properties (Note: Eligibility subject to human compliance review)
- Government-backed programs, where I can help you explore options under FHA, VA, or USDA financing (Note: Eligibility subject to human compliance review)
- Non-QM (non-qualified mortgage) products designed for alternative income documentation and self-employed borrowers
- Jumbo loan structures for higher-value homes across Tampa, St. Petersburg, and Clearwater neighborhoods
- Specialized financing solutions tailored for manufactured housing, condominium developments, and non-warrantable properties
Key Benefits of Partnering with an Independent Mortgage Broker
When you explore the distinction between an advisor vs broker, you quickly see that an independent professional serves as your personal representative in the wholesale marketplace. Instead of pushing one institution's proprietary loan product, an advisor-style broker evaluates the broader market to pinpoint favorable terms tailored directly to your financial goals.
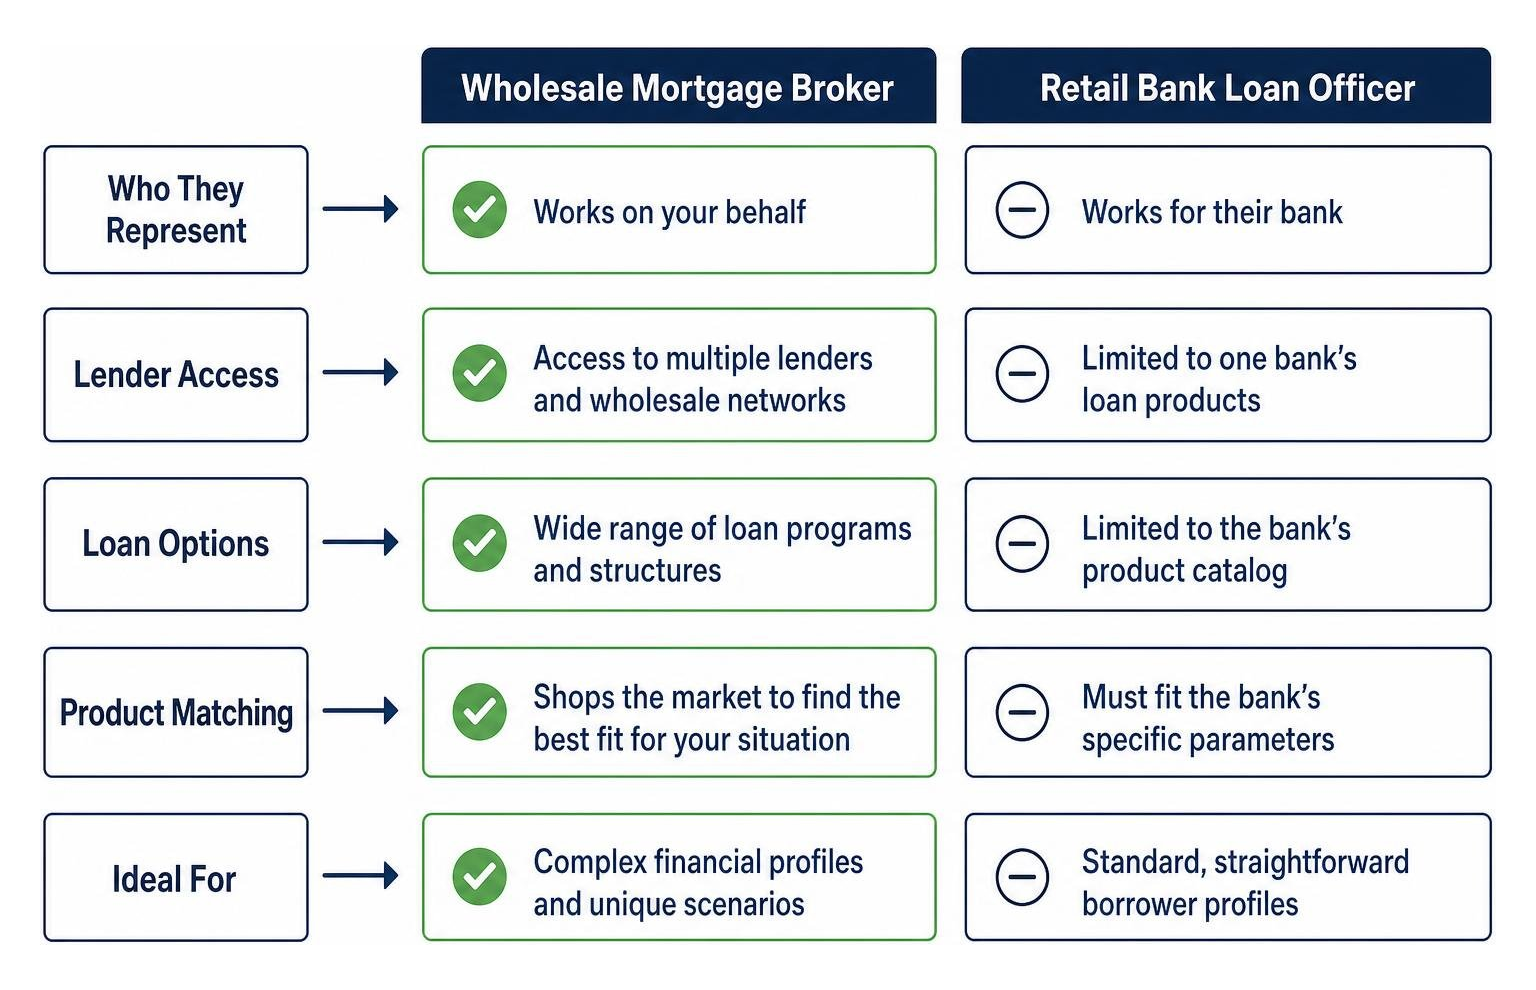
Broker vs Direct Bank: Navigating Complex Financial Profiles
Many Florida home buyers do not fit into a standard corporate underwriting box. Florida attracts seasoned business owners, 1099 independent contractors, remote tech workers, retirees, and international buyers who need customized structuring rather than rigid automated algorithms.
- Self-Employed Borrowers: Traditional retail banks often average two years of net taxable income from tax returns. For successful business owners, tax deductions and depreciation can substantially reduce reported net income, even when cash flow is strong. Independent brokers offer bank statement loan programs that evaluate 12 to 24 months of revenue deposits instead of taxable bottom lines.
- Foreign National Scenarios: International buyers purchasing vacation homes or investment properties in Florida frequently lack domestic credit files. Specialized wholesale loan programs evaluate foreign asset reserves and international banking references.
- Non-Traditional Scenarios: Whether managing recent career transitions, complex trust structures, probate property distributions, or past credit events, a specialized mortgage advisory service can connect your file with underwriting teams open to common-sense manual evaluation.
Why Working with the Best Rated Mortgage Brokers Saves Time and Stress
A smooth mortgage transaction requires coordinating multiple moving pieces: appraisal reviews, wind mitigation inspections, flood certifications, title searches, and automated underwriting findings. In competitive sub-markets across St. Petersburg, South Tampa, and Clearwater, unnecessary delays can create friction with sellers or jeopardize earnest money deposits.
Top-tier mortgage originators proactively organize your file before formal submission. By spotting potential underwriting questions early, collecting complete documentation upfront, and maintaining active communication with your real estate agent and closing title company, a broker eliminates administrative friction so you can focus on your upcoming move. Having an experienced professional who tracks milestone progress also ensures closing disclosures are delivered with sufficient time for thorough review.
How Top Brokers Structure Fees and the Loan Approval Timeline
Financial transparency is the cornerstone of a trustworthy lending relationship. Reputable mortgage professionals provide a clear breakdown of closing costs upfront through the official Loan Estimate document, helping you understand your out-of-pocket expenses early in the home buying journey.
Understanding Broker Compensation and Closing Cost Transparency
Federal lending regulations strictly govern mortgage broker compensation, protecting consumers from unfair practices. Brokers are compensated through one of two clear models:
- Lender-Paid Compensation: The wholesale lending institution pays the broker an agreed percentage after the loan successfully closes. Under this structure, the borrower does not pay a direct out-of-pocket origination fee to the broker.
- Borrower-Paid Compensation: The borrower pays the broker fee directly as part of closing costs, an option often selected when wholesale pricing discounts provide a strategic financial advantage over standard options.
Lending regulations prohibit dual compensation on the same transaction, which prevents hidden fees and arbitrary broker markups. Every third-party fee—such as property appraisal costs, title search fees, settlement charges, and state recording fees—is itemized in full detail on your disclosures. This transparency allows buyers to make fully informed comparisons between wholesale options and standard retail bank quotes.
Finding the Best Rated Mortgage Brokers for Specialized Scenarios
Different property transactions require distinct financing expertise:
- First-Time Homebuyers: Needs patient, educational guidance on down payment assistance programs, Florida homeowner insurance requirements, and escrow budgeting.
- Real Estate Investors: Requires analysis of debt service coverage ratios (DSCR), short-term vacation rental potential, and multi-unit portfolio financing.
- High-End & Luxury Buyers: Working with experienced high-end mortgage brokers is essential when structuring asset depletion programs, handling pledged asset financing, or securing jumbo loans for waterfront properties.
- Long-Term Financial Strategy: Connecting with mortgage financial advisors near me helps align your mortgage structure with your overall retirement planning and wealth preservation strategy.
Frequently Asked Questions About Mortgage Brokers
How do mortgage brokers access wholesale pricing and loan options?
Mortgage brokers partner directly with the wholesale lending divisions of nationwide financial institutions, regional banks, and specialized portfolio funds. Because brokers handle the upfront customer service, file setup, document collection, and pre-underwriting analysis, wholesale lenders do not carry the overhead of maintaining retail branch offices. These wholesale divisions pass on competitive pricing structures and specialized loan programs that are not available to consumers visiting standard retail bank branches.
How can borrowers verify track records and authentic client reviews?
When evaluating mortgage professionals, look for verified Google reviews and reputable platforms containing detailed, specific feedback about communication, responsiveness, and problem-solving abilities. In addition to client testimonials, cross-reference the loan originator’s background using the NMLS Consumer Access database. This public registry confirms licensing status, regulatory compliance history, and years of active industry practice.
What is the typical timeline for securing pre-approval through a broker?
While timing depends on document readiness and income complexity, an initial review of your credit history, tax returns, and asset statements can often be completed within one to two business days. Straightforward W-2 wage earners with standard documentation may receive a pre-approval quickly, while complex self-employed files involving multiple business entities, balance sheets, and corporate tax schedules may require additional time for an in-depth cash flow analysis.
Next Steps in Your Home Financing Journey
Securing a home loan is one of the most substantial financial decisions you will make. Navigating Florida's dynamic real estate market requires an educated, transparent approach tailored to your exact property goals and financial picture.
Whether you are purchasing a primary residence, acquiring an investment property, or exploring refinancing opportunities in Tampa, St. Petersburg, Clearwater, or across Florida, let us review your financing options together. Connect with Home Loan Advisors to start an informative conversation about what financing solutions make sense for your situation.
Josh Jampedro | Vice President | NMLS #1082889
Equal Housing Lender
Connect on social: Instagram @joshjampedro | YouTube @BetterRate | LinkedIn linkedin.com/in/josh-jampedro | Facebook FLHomeLoanAdvisors | joshjampedro.com
Mortgages are complex so let me give you the tools you need to make the right decisions.