The Ultimate Guide to Local and Recommended Mortgage Advisors
Find Mortgage Financial Advisors Near Me for Clear Home Loan Guidance
Mortgage financial advisors near me can help you connect your home loan choice to your budget, savings, debt, and long-term plans. For a Tampa Bay buyer comparing homes in Tampa, St. Petersburg, Clearwater, or surrounding communities, the right local professional can make the process feel less like guesswork and more like a clear financial decision.
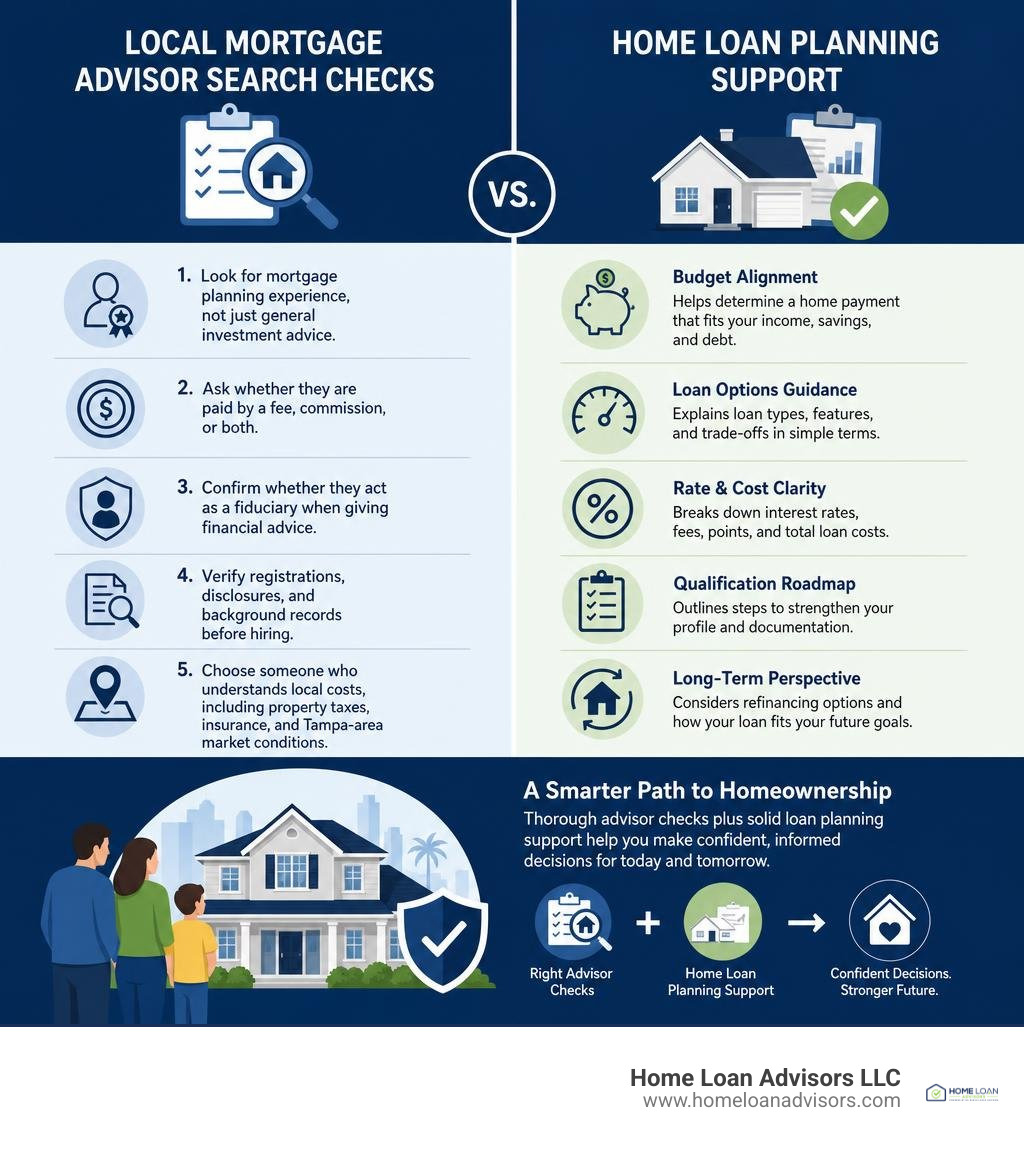
Start with these quick checks:
- Look for mortgage planning experience, not just general investment advice.
- Ask whether they are paid by a fee, commission, or both.
- Confirm whether they act as a fiduciary when giving financial advice.
- Verify registrations, disclosures, and background records before hiring.
- Choose someone who understands local costs, including Florida property taxes, homeowners insurance, flood insurance considerations, and Tampa Bay market conditions.
A financial advisor can help you decide what home payment fits your wider financial life. A mortgage-specific advisor or loan professional focuses more directly on loan options, rates, qualification, and refinancing. In some cases, working with both can provide a fuller view before you commit to a large, long-term debt.
This guide explains how to find, compare, and vet local mortgage advisors so you can move forward with fewer surprises and a plan that supports your goals.
Understanding Financial Advisors vs. Mortgage-Specific Advisors
When you decide to buy a home, you quickly realize that home financing is about far more than grabbing an interest rate off a billboard. You are taking on a major financial obligation that can affect your cash flow, savings, taxes, insurance costs, and long-term plans. Naturally, many buyers start searching for mortgage financial advisors near me to make sure the decision fits the rest of their financial life.
However, a common point of confusion is deciding who to talk to: a general financial advisor, a mortgage advisor, or a licensed loan officer?
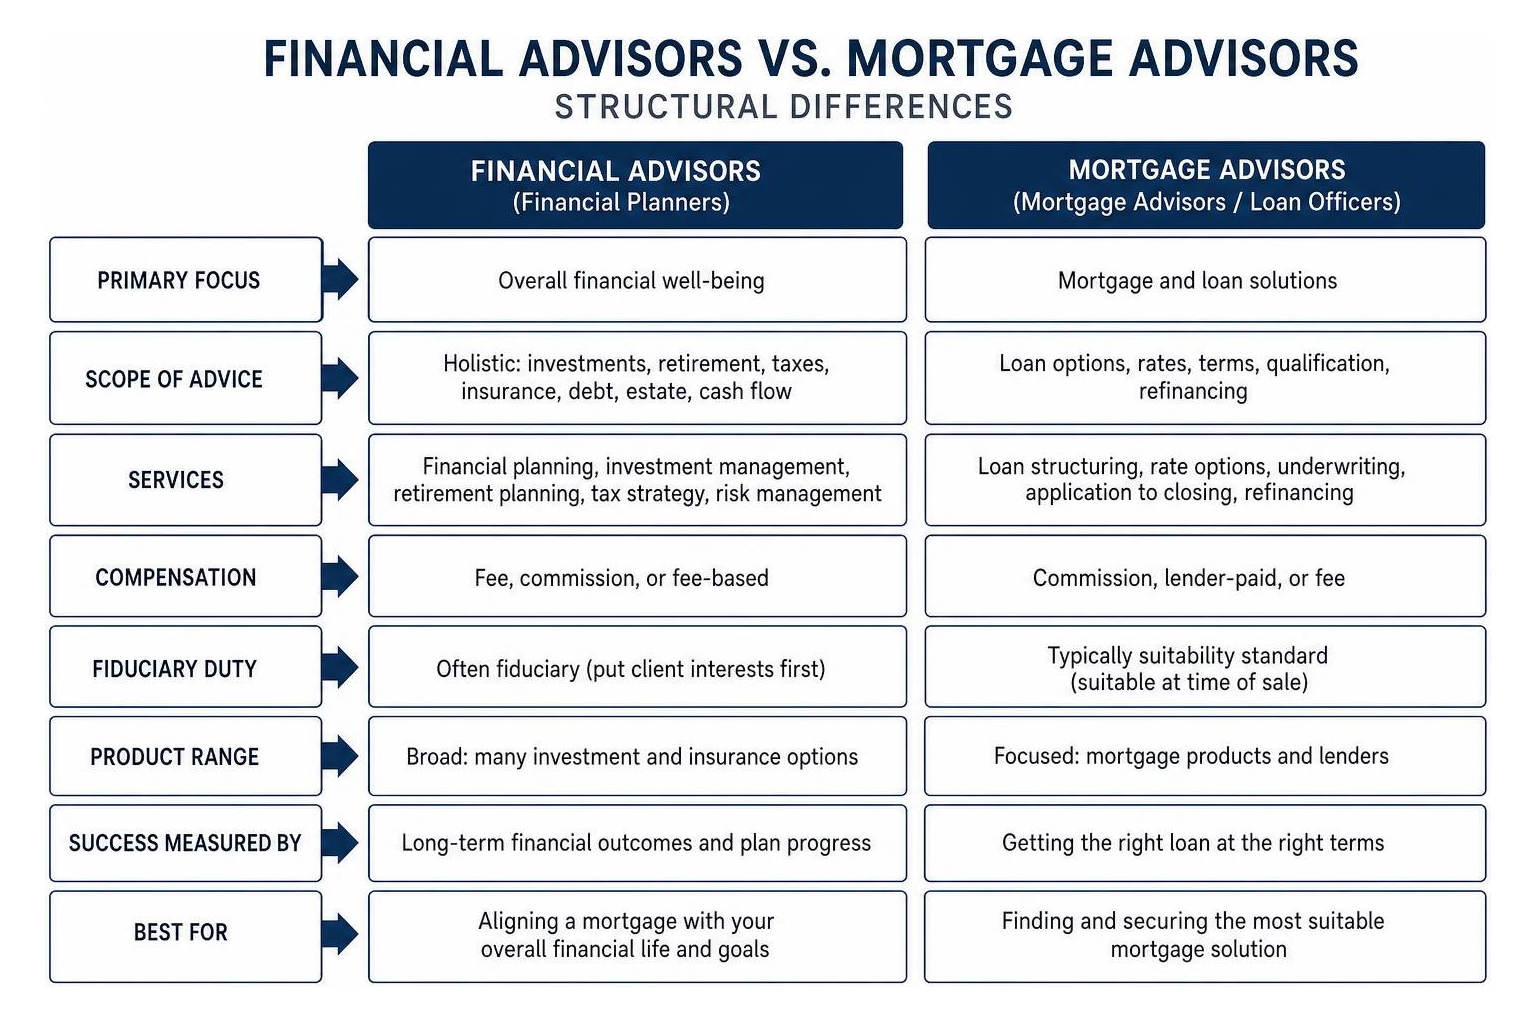
- Financial Advisors & Financial Planners: These professionals evaluate your entire financial picture. They analyze investment accounts, retirement trajectories, tax strategies, debt management, and emergency reserves. When it comes to real estate, a financial planner evaluates how taking on a mortgage may affect your plan to retire, invest, or keep enough cash available after closing. They look at home equity as one asset class among many. Registered investment advisors (RIAs) generally operate under a legal fiduciary duty when providing advisory services, meaning they must place your financial interests ahead of their own.
- Mortgage Advisors & Loan Officers: A mortgage-specific advisor or loan officer focuses on loan structure, underwriting rules, credit qualification, interest rate options, and borrowing mechanisms. Their role is to help you compare loan structures that may fit your purchase or refinance goals. Compensation and legal duties can vary, so it is worth asking how the professional is paid and what standard applies to the advice they provide.
At Home Loan Advisors, we connect mortgage guidance with the bigger financial picture. Instead of only discussing a loan product, we look at how your mortgage may fit into your debt management, cash flow, and home equity goals.
Financial Advisors and Home Loan Integration
Buying a house without integrating your mortgage into your holistic plan is like buying a high-performance sports car without checking if you can afford the auto insurance or premium fuel. Proper integration helps keep home financing from putting too much pressure on your everyday lifestyle.
Key areas where financial planning intersects with home loans include:
- Cash Flow Optimization: Reviewing your monthly principal, interest, taxes, and insurance (PITI) against your take-home pay, savings goals, and regular expenses.
- Liquidity Management: Avoiding a house-poor situation. Draining too much from liquid savings for a larger down payment can leave you vulnerable if a roof, plumbing, or air conditioning issue comes up after closing.
- Down Payment Strategies: Weighing the benefits of a smaller down payment versus a larger one. In some situations, retaining cash in savings or investments may be worth comparing against tying up extra cash in home equity to reduce mortgage insurance.
- Long-Term Financial Goals: Aligning loan terms with life milestones like funding college tuition, launching a business, or planning for retirement.
Specialist Certifications and Standards
As you evaluate professionals, you will encounter an alphabet soup of acronyms after their names. Understanding these credentials helps you know what kind of advice you are paying for:
- CFP (Certified Financial Planner): CFPs complete board examinations and experience requirements covering comprehensive financial planning, taxes, investments, insurance, and estate strategies. CFP professionals must act as fiduciaries when providing financial advice.
- CFA (Chartered Financial Analyst): CFAs specialize heavily in investment analysis, portfolio management, and corporate valuation. They may be helpful for complex asset management, though they are often less focused on personal budgeting or debt structuring.
- CPA (Certified Public Accountant): CPAs are tax experts. When buying real estate or tapping equity, a CPA can provide guidance on itemized deductions, capital gains considerations, and mortgage interest tax rules.
- IAR (Investment Adviser Representative): IARs work for registered investment advisory firms and provide tailored investment advice. They owe clients a legal fiduciary duty under state or federal law.
How Mortgage Financial Advisors Near Me Guide Your Home Buying Strategy
Searching for mortgage financial advisors near me gives you access to localized expertise when crafting a home buying strategy. Getting a loan approved is only part of the process; making sure the debt fits your budget without causing financial strain is where real advisory planning matters.
Your advisor evaluates several key areas:
- Budget Planning: Rather than relying solely on the maximum loan amount a lender may pre-approve, a mortgage advisor builds a bottom-up budget reflecting your actual lifestyle, travel plans, childcare costs, savings goals, and Florida insurance costs.
- Debt-to-Income (DTI) Ratio Management: Underwriting guidelines consider how your monthly debts compare with your income. An advisor can help you understand how credit cards, auto loans, student loans, or other obligations may affect your mortgage options.
- Mortgage Rate Evaluation: Comparing fixed-rate loans, adjustable-rate mortgages (ARMs), temporary rate buydowns, and discount point options to see which structure may match your expected timeline in the property.
To learn more about selecting loan specialists who take this educational approach, review our guide on How to Find the Right Loan Officer.
Mortgage Planning and Refinancing Support
A home loan is not a set-it-and-forget-it transaction. As economic environments evolve and interest rates shift, active mortgage planning may help you compare whether a refinance, recast, or term adjustment makes sense.
When rate trends change, a mortgage advisor can model refinancing options to estimate your break-even point, which is when projected savings may exceed upfront closing costs. They can also walk through term restructuring, such as moving to a shorter or longer term depending on your cash flow and equity goals. For tax questions, it may also make sense to coordinate with a CPA, especially if you are considering a cash-out refinance or other equity strategy.
Local Market Insights and Neighborhood Dynamics

National real estate advice frequently misses the reality of local markets. A localized advisor brings crucial context to your home search across Tampa, St. Petersburg, Clearwater, Brandon, Riverview, Wesley Chapel, Palm Harbor, and nearby Tampa Bay communities:
- Regional Housing Trends: Understanding whether local property pricing is moving quickly or stabilizing helps you think through offer strategy and financing flexibility.
- Property Tax Variations: In Tampa Bay, property taxes and municipal assessments can vary across Hillsborough, Pinellas, Pasco, and surrounding counties, which can affect your monthly escrow payment.
- Insurance Standards: Local advisors understand Florida cost drivers, such as flood insurance requirements, wind coverage considerations, and homeowners insurance availability in coastal or low-lying areas.
- Local Underwriting Nuances: Regional lenders and local mortgage firms may be familiar with Florida condominium associations, neighborhood comparable sales, and state-specific disclosure requirements.
Advisor Fee Structures and Vetting Credentials
Before you hire any financial or mortgage professional, understand how they make money. Compensation structures can influence the recommendations you receive.
Financial planning and investment fees generally fall into three categories:
- Assets Under Management (AUM): Advisors manage your investment portfolio and charge a percentage of total assets managed.
- Flat Retainer Fees: Some advisors charge a flat project fee or ongoing retainer for written financial planning.
- Hourly Rates: Some advisors offer standalone mortgage planning, debt consultation, or home buying strategy by the hour.
| Fee Structure / Regulatory Standard | Typical Cost Range | Primary Compensation Source | Regulatory Oversight Body | Legal Duty to Client |
|---|---|---|---|---|
| Fee-Only Advisory (AUM) | Varies by firm and account size | Direct client fees | SEC or state regulator | Fiduciary Standard |
| Flat-Fee Financial Plan | Varies by scope and advisor | Direct client fees | SEC or state regulator | Fiduciary Standard |
| Hourly Advisory Services | Varies by advisor and complexity | Direct client fees | SEC or state regulator | Fiduciary Standard |
| Fee-Based / Broker-Dealer | Varies by fees and commissions | Client fees plus possible product commissions | FINRA/ state regulators | Suitability, Regulation Best Interest, or fiduciary standard depending on role |
| Robo-Advisor Platform | Varies by platform | Direct client fees | SEC | Fiduciary Standard |
Note: Additional costs like underlying fund expense ratios or custodial fees may apply in investment portfolios. Ask for the full fee schedule in writing before hiring an advisor.
Fee-Only vs Fee-Based Advisory Services
Understanding the difference between fee-only and fee-based is essential to managing potential conflicts of interest:
- Fee-Only Advisors: These professionals are compensated through direct payments from you, the client. They do not accept sales commissions, kickbacks, referral fees, or soft-dollar compensation from financial institutions or product issuers. This model can reduce financial conflicts when they recommend loan structures or financial strategies.
- Fee-Based Advisors: These professionals charge a direct client fee but may also earn commissions by selling specific financial products, such as annuities, life insurance policies, or proprietary financial products. Many fee-based advisors maintain high professional standards, but the dual revenue model creates a potential incentive to recommend commission-generating products.
Background Verification and Regulatory Checks
Trusting someone with your home financing strategy requires thorough vetting. Financial regulatory frameworks give you access to public disclosure documents.
Regulatory bodies govern firms based on size and business model. The U.S. Securities and Exchange Commission (SEC) and state regulators oversee investment advisory firms, while FINRA oversees many broker-dealer activities.
Request and review Form ADV Part 2 when working with a registered investment advisory firm. This required public filing outlines the firm's fee schedule, potential conflicts of interest, operating methods, and legal or disciplinary history.
Step-by-Step Selection Process: Finding Mortgage Financial Advisors Near Me
Finding the right local financial or mortgage professional does not have to be overwhelming. A structured step-by-step process keeps you focused on finding a reliable expert.
- Define Your Scope: Decide whether you need broad financial planning, such as investment management, retirement planning, and tax planning, or focused home loan guidance, such as pre-approval, loan structuring, refinancing options, and Florida insurance considerations.
- Gather Local Recommendations: Tap your local network, real estate agents, accountants, or friends in the Tampa Bay area. You can also search certifying board databases, such as the CFP Board or SEC IAPD, using your local ZIP code.
- Perform Initial Screening: Cross-reference prospective names against regulatory database checks to review their credentials and disciplinary history.
- Schedule Initial Consultations: Many advisory and mortgage firms offer an introductory conversation at no cost. Use this meeting to evaluate their communication style, local knowledge, and willingness to explain the tradeoffs.
Evaluating Local Mortgage Financial Advisors Near Me
When evaluating candidates, look beyond shiny brochures and evaluate their real-world capabilities:
- Portfolio Compatibility: Make sure the advisor frequently works with clients in your financial stage and home-buying situation. An advisor focused mainly on complex estate planning may not be the right fit for a buyer comparing mortgage options and Florida closing costs.
- Local Market Experience: Confirm they understand Tampa Bay market dynamics, local property tax structures, homeowners insurance issues, flood zone considerations, and Florida home buying programs.
- Client Feedback & Reputation: Check public reviews and client feedback to assess how responsive, transparent, and helpful they are during the mortgage process. You can also read feedback on our Reviews page to see how an education-driven approach can help home buyers ask better questions.
Questions to Ask Mortgage Financial Advisors Near Me
When you sit down with a prospective advisor or mortgage professional, bring this quick interview checklist:
- How are you compensated, and are there any referral fees or commissions I should understand?
- Are you acting as a fiduciary for this advice? If so, will you put that in writing?
- How do you account for Florida homeowners insurance, flood insurance, taxes, and escrow changes?
- What loan structures may fit my situation, and what tradeoffs should I understand?
- Does pre-approval depend on later underwriting, appraisal, documentation, and property review?
- What disclosures, licenses, or registration records should I review before moving forward?
Frequently Asked Questions About Mortgage Advisors
How do financial advisors charge for mortgage planning advice?
Financial advisors handle mortgage planning in a few different ways:
- Hourly Advisory Rates: Some fee-only planners offer dedicated debt and home buying advice by the hour.
- Flat Financial Plan Fee: Some advisors provide standalone written financial plans that incorporate home purchase strategy, while others use broader annual retainer agreements.
- Assets Under Management (AUM) Model: If an advisor manages your investment portfolio, mortgage and debt analysis may be included as part of ongoing wealth planning.
- Mortgage Lenders & Loan Officers: Licensed loan officers provide loan selection, rate quotes, and pre-approval guidance, often earning compensation through loan origination structures if a loan closes.
What is the difference between a financial advisor and a mortgage advisor?
A general financial advisor focuses on your broader long-term wealth strategy, including investment accounts, retirement savings, tax planning, estate planning, and overall budgeting. They evaluate whether buying a house fits into your lifetime financial plan.
A mortgage advisor or loan specialist focuses specifically on home financing mechanisms, loan underwriting requirements, credit optimization, debt structuring, rate locks, and refinancing options. While a financial planner asks, "How much home fits my plan?" , a mortgage specialist asks, "How can we structure this loan in a way that fits your goals and the available options?"
Pre-approval can be a useful planning step, but it is not final loan approval. Final approval depends on underwriting, documentation, appraisal, property review, and other lender requirements.
How can I verify if an advisor is a legal fiduciary?
You can confirm an advisor's legal fiduciary status by taking three simple verification steps:
- Ask for a Written Fiduciary Oath: Request that the advisor sign a simple statement confirming they act as a fiduciary for the services they provide to you.
- Inspect Form ADV Part 2: Download the firm's Form ADV from the SEC's Investment Adviser Public Disclosure (IAPD) database or state regulatory site. Read Item 5 (Fees) and Item 10 (Financial Industry Activities) to check for conflicts of interest or commission-based sales.
- Check Registration & Credentials: Confirm whether the advisor is an Investment Adviser Representative (IAR) or holds credentials like CFP, which legally or ethically enforce fiduciary standards when providing financial advice.
Conclusion
Taking on a mortgage is one of the biggest financial steps many people take. Partnering with professionals who emphasize planning, local Tampa Bay knowledge, and fee transparency can help you understand how a home loan may fit your budget, savings, and long-term goals.
Josh Jampedro is a Tampa, Florida mortgage broker and vice president with more than 1,000 closed transactions and more than 10 years of experience. Home Loan Advisors LLC works with buyers and homeowners across Tampa, St. Petersburg, Clearwater, and surrounding Florida communities with an education-first approach.
If you want to talk through what may make sense for your situation, you can start a conversation through Get a Quote, or learn more about available guidance at Explore Home Loan Advisors Solutions.
Official Josh Jampedro platforms: Instagram @joshjampedro, YouTube @BetterRate, LinkedIn linkedin.com/in/josh-jampedro, Facebook FLHomeLoanAdvisors, and website joshjampedro.com.
Mortgages are complex so let me give you the tools you need to make the right decisions.