Navigating Jumbo Loans in Tampa Bay: High End Mortgage Brokers Guide
How High End Mortgage Brokers Help With Complex Jumbo Financing
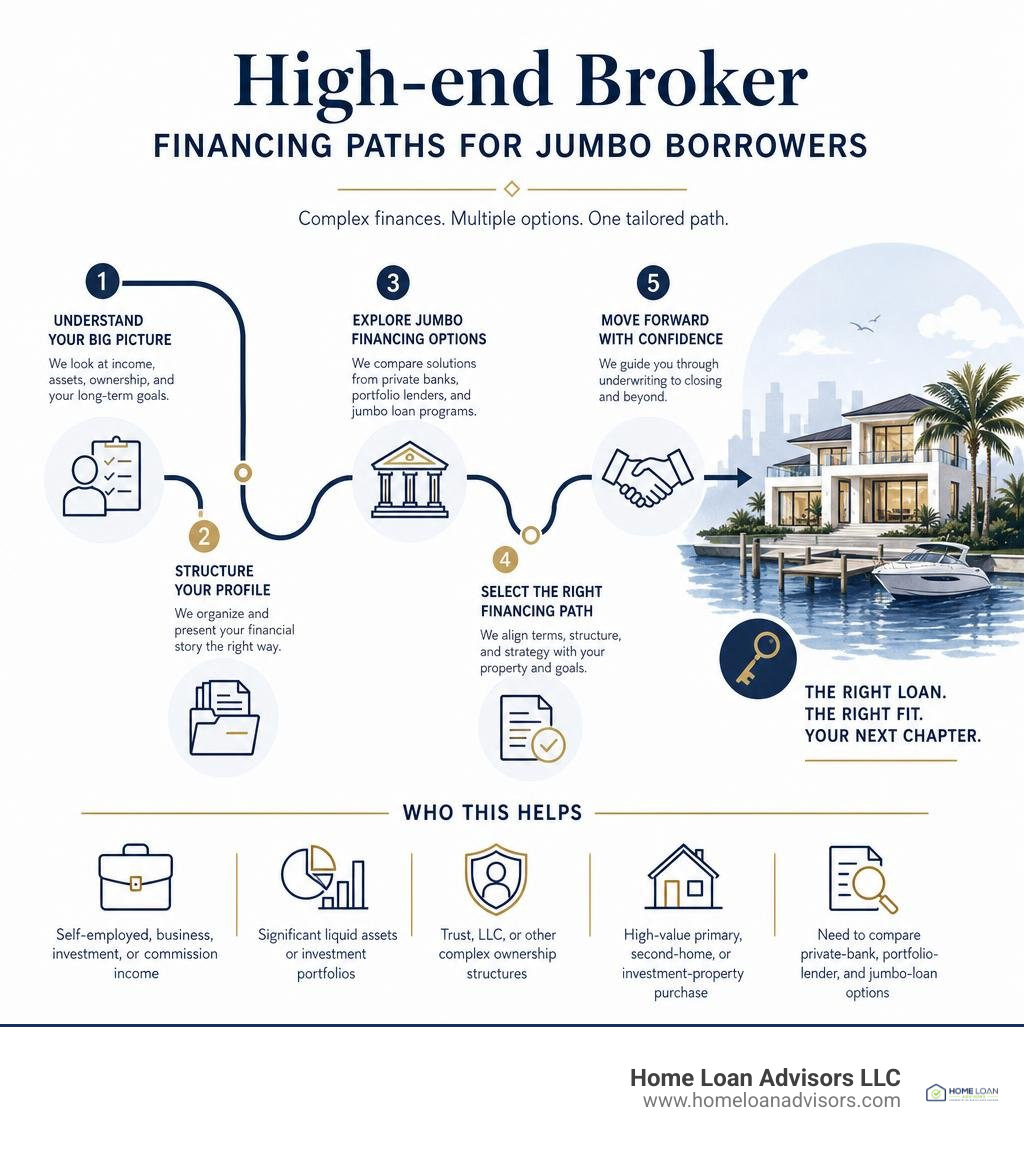
High end mortgage brokers help buyers and owners of higher-value Florida properties find financing that fits complex income, assets, and ownership structures. They are most useful when a standard mortgage application does not tell the full financial story.
Quick answer: A high-end broker may be a good fit when you need a jumbo loan for a Tampa, St. Petersburg, or Clearwater property and have circumstances such as:
- Self-employed, business, investment, or commission income
- Significant liquid assets or investment portfolios
- A trust, LLC, or other complex ownership structure
- A high-value primary, second-home, or investment-property purchase
- A need to compare private-bank, portfolio-lender, and jumbo-loan options
The goal is not simply to find a loan. It is to understand how the property, income, assets, cash reserves, and long-term plans fit together before choosing a financing path.
I'm Josh Jampedro, NMLS #1082889, a Tampa mortgage broker with over 10 years of experience and more than 1,000 closed transactions helping Florida buyers make sense of complex mortgage options.
What Distinguishes High End Mortgage Brokers from Standard Lenders?
The Role of High End Mortgage Brokers in Luxury Property Acquisition
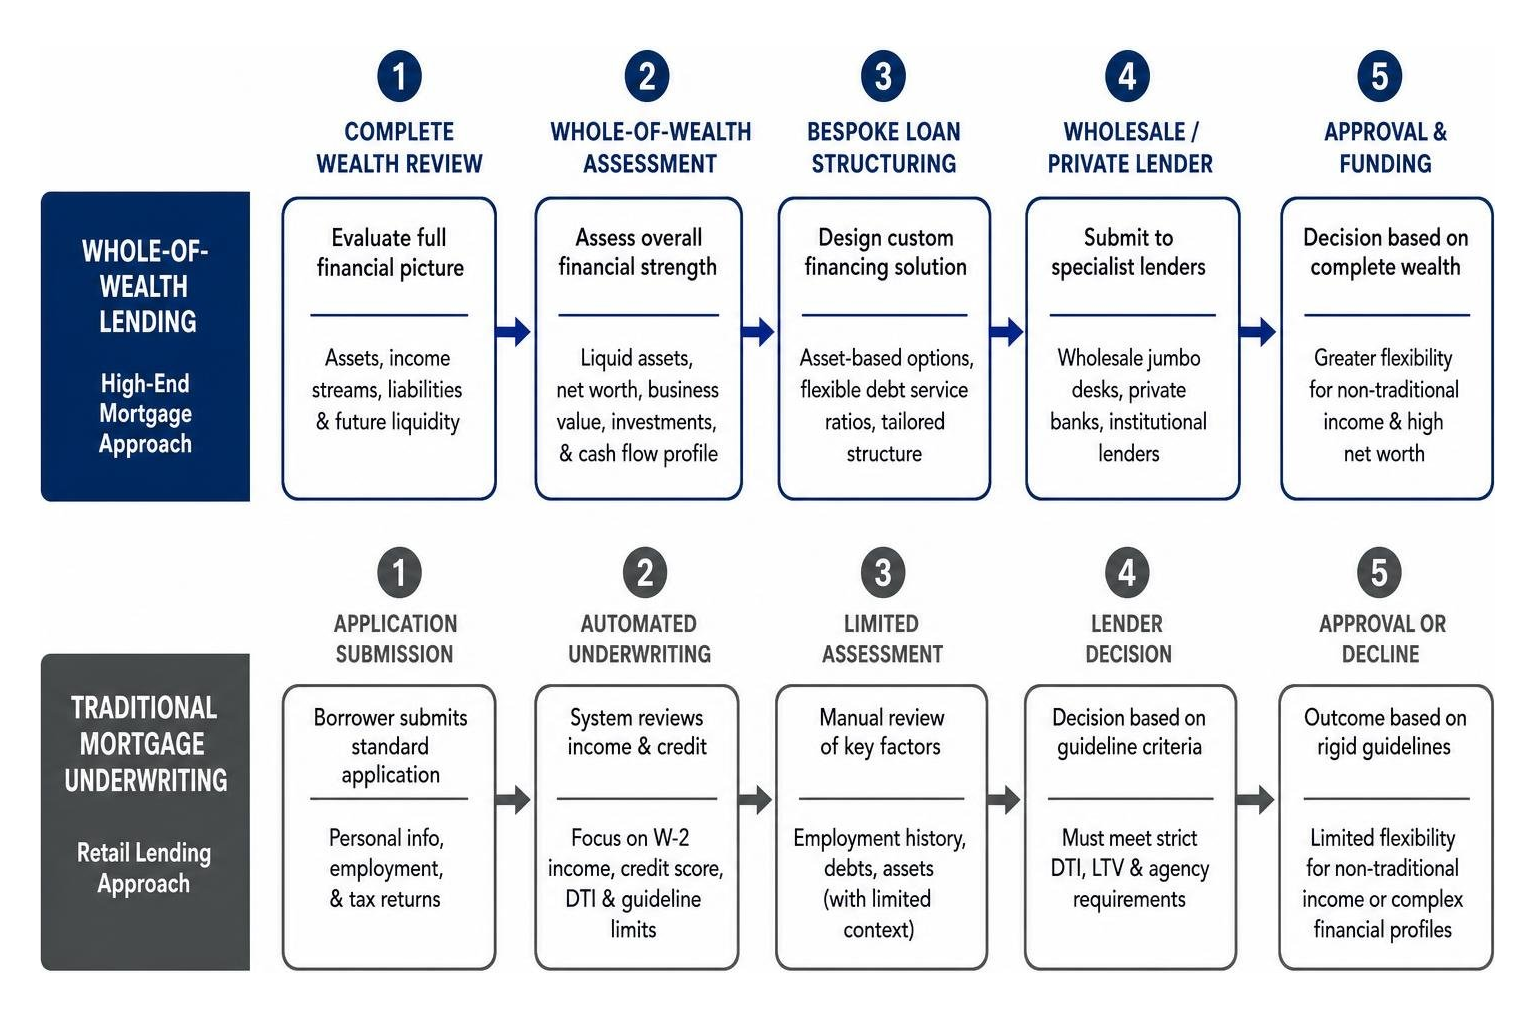
When purchasing high-value real estate along the Tampa Bay coast or in established luxury neighborhoods across Florida, traditional retail lending guidelines can feel restrictive. Standard retail mortgage channels often rely on automated underwriting systems designed for straightforward W-2 income scenarios. When your financial picture includes private business distributions, capital gains, or foreign assets, those rigid frameworks often fall short.
This is where specialist high end mortgage brokers step in. Instead of forcing a complex financial profile into a rigid box, high-end brokers evaluate the complete wealth picture. We work directly with wholesale jumbo desks, private banks, and institutional lenders to craft bespoke underwriting strategies.
Whether you are securing financing for a luxury home purchase in St. Petersburg or exploring options for Jumbo Home Loans, a specialist advisor looks at asset-based qualification, unencumbered liquid holdings, and non-traditional income streams to present a compelling credit narrative to underwriters.
Client Profiles Served by Elite Mortgage Advisors
Elite mortgage brokers work with clients whose financial structures demand elevated expertise. These client profiles often include:
- High-Net-Worth Individuals (HNWIs) & Ultra-HNWIs: Borrowers with multi-million dollar asset portfolios who prefer not to liquidate equity or trigger tax liabilities just to purchase a primary residence or vacation retreat.
- Self-Employed Entrepreneurs & Business Owners: Executives who retain earnings within corporate entities or utilize complex tax structures that show modest taxable W-2 income on paper.
- Foreign Nationals & International Residents: Global investors acquiring luxury real estate in competitive metropolitan or coastal markets who require specialized underwriting expertise.
- Tampa Bay Luxury Property Buyers: Buyers acquiring high-end coastal estates across Davis Islands, Belleair, Snell Isle, or Clearwater Beach who need custom loan structures to match local market dynamics.
Navigating multi-million dollar transactions requires deep experience across specialized private banking networks and flexible underwriting channels tailored for international or high-net-worth buyers.
Private Bank Mortgages vs. Conventional Mortgage Lending
Affordability Assessment and High-Net-Worth Qualification Standards
Standard mortgage underwriting relies heavily on strict debt-to-income (DTI) caps tied strictly to tax return income. Conventional lending guidelines, including those for standard Conventional Home Loans, often limit debt service ratios based on strict Fannie Mae or Freddie Mac parameters. Note: Program eligibility language for Conventional loans is subject to standard compliance review.
Private banking relationships and specialized jumbo channels operate differently. Overseas regulatory frameworks like the Financial Conduct Authority’s MCOB 3A rules explicitly enable lenders to assess high-net-worth clients based on whole-of-wealth affordability rather than standard income multiples. In practice, a borrower demonstrating substantial liquid assets or net wealth (£300,000+ annual income or £3,000,000+ net assets under UK standards, or equivalent multi-million dollar liquidity in U.S. markets) can access flexible debt service ratios. Lenders evaluate overall financial strength, future liquidity events, or dividend projections rather than past tax returns alone.
Asset Reserve Mechanics and Portfolio Financing
Another key difference between standard lenders and private institutions involves asset transfers and collateralized lending. Private banks often encourage or require Assets Under Management (AUM) transfers—placing a percentage of liquid assets under their management—in exchange for lower headline mortgage interest rates.
Borrowers must weigh the overall value of relationship pricing against wealth management management fees (which often range from 0.5% to 1.5% annually). In many cases, combining a residential jumbo mortgage at a lower loan-to-value (LTV) ratio with a Lombard lending facility—a line of credit secured directly against a liquid stock portfolio—provides greater financial flexibility than liquidating investments.
| Financing Approach | Qualification Basis | Asset Management Requirement | Typical LTV Ranges | Flexibility for Non-Standard Income |
|---|---|---|---|---|
| Standard Jumbo Loan | Strict DTI & Tax Return Income | Liquidity reserve verification only | 70% – 80% | Limited; relies on standard documentation |
| Private Bank (AUM Transfer) | Whole-of-Wealth & Asset Base | 25% – 50% of loan amount in AUM | 65% – 90% | High; customized debt-service ratios |
| Dry Private Bank Lending | Balance Sheet & Liquid Holdings | No asset transfer required | 60% – 75% | Moderate to High; slightly higher rate pricing |
| Lombard / Portfolio Credit | Pledged Securities / Equity | Assets pledged as loan collateral | Varies based on asset volatility | High; liquidity draw without liquidating assets |
Specialized Financing Solutions for High-Value Properties
High-Value Property Financing and Asset-Backed Jumbo Loans
Luxury property acquisitions require financing tools tailored to unique market conditions. High-value property financing relies on customized jumbo debt structures that extend beyond off-the-shelf loan products.

When financing luxury waterfront homes along the St. Petersburg coastline or large estates in Tampa, high-end brokers coordinate asset-backed lending strategies. This might involve using stock portfolios, trust assets, or business valuations to support loan approval. For investors managing multiple assets, short-term bridging finance can secure a property quickly before transitioning into long-term debt through a standard Refinance.
Structuring High End Mortgage Brokers Services for Complex Wealth
Structuring debt for complex wealth profiles requires meticulous detail. High-end mortgage brokers coordinate with financial planners, tax professionals, and legal counsel to establish loan structures that protect cash flow and respect estate planning goals.
Common capital structures include:
- Flexible Repayment Options: Structuring interest-only periods on high-LTV jumbo loans to preserve capital for active investment opportunities.
- Hybrid Rate Products: Utilizing an Adjustable Rate Mortgage for short- to medium-term holding strategies, or locking in long-term security with a 30 Year Fixed Mortgage or 15 Year Fixed Mortgage.
- Special Purpose Vehicles (SPVs) & Trusts: Structuring loan contracts under domestic or international entity structures, such as an LLC or revocable trust, to maintain privacy and facilitate asset protection.
Navigating complex private bank tiers for high-value purchases requires an advisory approach focused on custom wealth financing solutions for discrete estate purchases.
When to Use a Specialist Broker vs. Direct Private Banks
Evaluating Direct Bank Relationships versus Whole-of-Market Advisory
A common question for high-net-worth clients is whether to approach their existing wealth management bank directly or hire an independent high-end broker.
Going directly to a private bank makes sense if you already maintain substantial liquid assets with that institution and prefer to keep your financial accounts under one roof. However, direct private banks offer their own proprietary loan products.
Working with an independent wholesale mortgage broker provides access to broader market options. A specialist broker can compare dry lending options, which are mortgages without AUM transfer requirements, against relationship-priced private bank offers. Obtaining a solid Pre Approval through a flexible wholesale channel may help buyers bid with more clarity on prime real estate in Clearwater, Tampa, or St. Petersburg without committing capital prematurely.
For general consumer education on comparing mortgage options, the Consumer Financial Protection Bureau's home loan resources can also be a helpful reference.
Expert Wealth Advisory and Case Execution Strategies
High-end mortgage execution is about risk mitigation and expert navigation. Large property transactions involve detailed appraisals, complex legal reviews, and stringent title checks.
A boutique brokerage acts as an advocate throughout underwriting. By using interactive tools like a modern Mortgage Calculator to stress-test various scenario outputs and coordinating directly with family offices, brokers help ensure that real estate debt fits into the client's broader balance sheet.
Frequently Asked Questions About High-Value Property Financing
What qualifies a borrower for high-end private bank mortgages?
Qualification typically centers on total balance sheet strength rather than W-2 income alone. Lenders look for significant net worth, clean global asset disclosures, verifiable liquid reserves, and established credit histories. While minimum loan thresholds often start at $1 million+, whole-of-wealth underwriting allows lenders to account for business equity, investment accounts, and future liquidity events.
Do private bank jumbo loans require asset management transfers?
Not in every case. While many private banks offer reduced interest rates in exchange for moving investment portfolios (AUM transfers), selected lenders provide "dry lending" facilities. Dry lending allows borrowers to secure high-value property debt without transferring investment assets, though interest rate pricing may be adjusted to account for the lack of an ongoing management relationship.
How long does a complex jumbo mortgage completion take?
Timelines vary based on property type, title structures, legal review requirements, and appraisal complexity. While standard home loans can proceed more straightforwardly, complex jumbo or private bank mortgages involving multi-jurisdictional trusts or entity reviews require additional time to complete underwriting and legal verification.
Navigating High-Value Mortgage Decisions in Florida
Securing high-value property financing along the Florida coastline demands an educated, strategic approach. Whether you are expanding a real estate portfolio in Tampa Bay, acquiring a luxury waterfront residence in St. Petersburg, or evaluating jumbo loan structures for a Clearwater estate, working with an experienced mortgage advisor helps bring clarity to complex financial landscapes.
To learn more about our education-focused guiding philosophy, visit our About Us page or reach out directly through our Contact page to review your specific financing goals. You can also explore our broader resources on the official Home Loan Advisors website.
Equal Housing Lender. Josh Jampedro, NMLS #1082889. Home Loan Advisors LLC provides education-focused mortgage guidance and personalized loan solutions across Florida and Wisconsin.
Mortgages are complex so let me give you the tools you need to make the right decisions.