Mortgage Advice in Tampa That Starts With Your Plan
Find the Right Mortgage Advisory Service for Your Tampa Home Purchase
A mortgage advisory service helps you compare home loan options, understand what you can afford, and move from early planning to closing with fewer surprises.
For a first-time buyer in the Tampa area, the best service is usually one that offers:
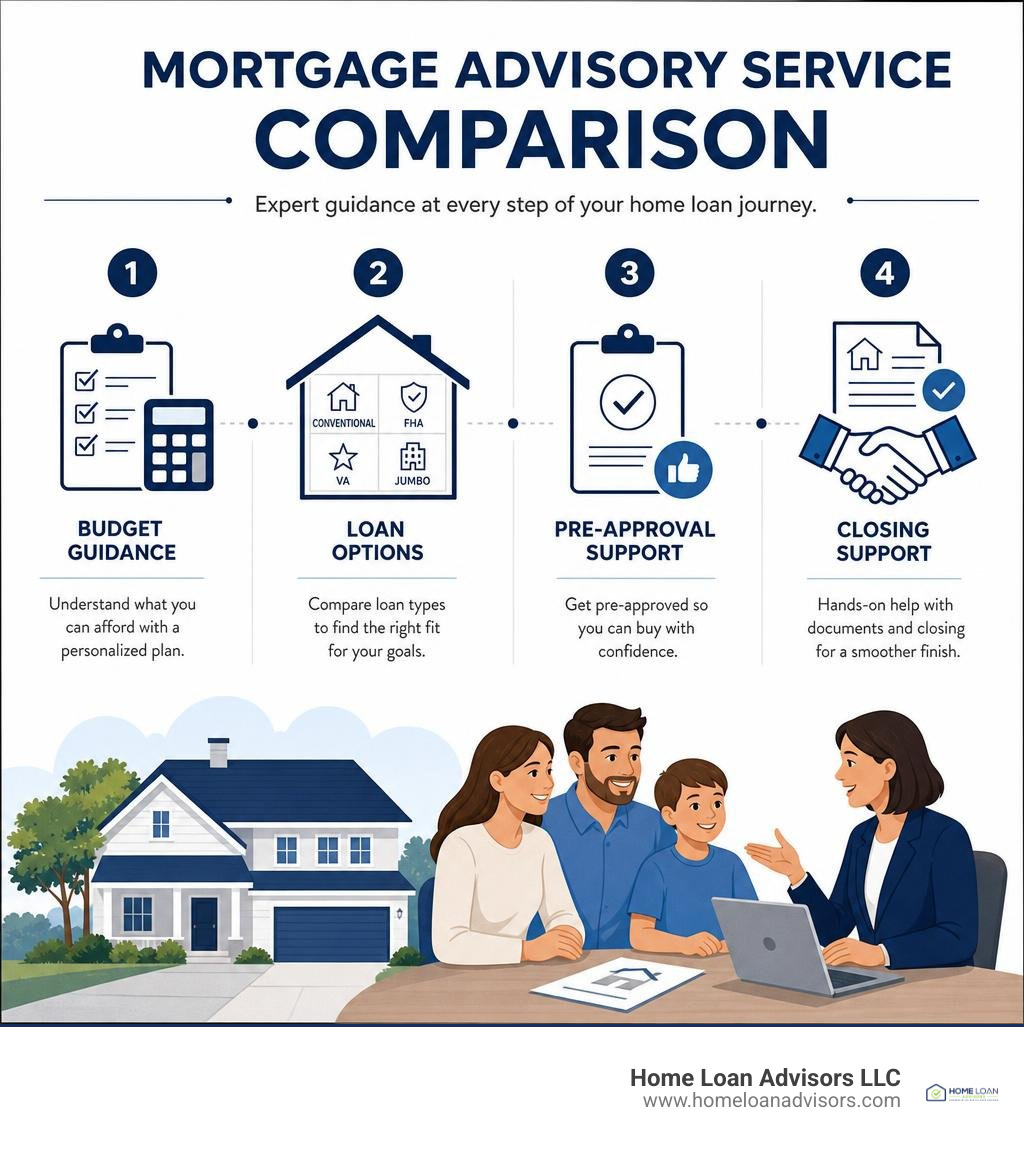
- Personal budget guidance based on income, debts, credit, down payment, taxes, insurance, and HOA fees.
- Clear loan comparisons across options such as conventional, FHA, VA, and jumbo mortgages.
- Pre-approval support before you make an offer on a home.
- Hands-on document and underwriting help to reduce avoidable delays.
- Plain-English answers about rates, closing costs, mortgage insurance, and monthly payment changes.
A strong advisor does more than quote an interest rate. They help you see the full cost of buying and owning a home, spot issues early, and choose a loan that fits both your current budget and longer-term goals.
This guide compares the kinds of mortgage advisory services available and explains what to look for before choosing one.
Types of Mortgages and Key Benefits of a Mortgage Advisory Service
Buying a home in 2026 can feel like solving a Rubik's cube blindfolded. Between changing interest rates, shifting underwriting criteria, and endless loan acronyms, having an expert in your corner matters. That is where a professional mortgage advisory service makes all the difference.
When you begin your search for financing, you will encounter three main categories of advisors:
- Independent Mortgage Brokers: These independent advisors have access to products across the entire lending market. They are not tied to a specific bank or limited panel, allowing them to search hundreds of mortgage deals to find the exact loan structure that fits your financial profile.
- Restricted Advisors: These specialists operate from a curated panel of preferred lenders. While they compare multiple products, their selection is limited to partners on their specific roster.
- Single-Lender Advisors: Working directly for a bank or credit union, these loan officers only offer products from their own institution.
Whether you are seeking regulatory protection under established conduct authority guidelines or working with licensed loan specialists in the United States, utilizing an independent advisory approach offers distinct advantages. To learn more about our commitment to educational, transparent mortgage guidance, visit our page About Us.
Choosing an Independent Mortgage Advisor
Choosing an independent mortgage broker gives you access to loans you might never find on your own. Check that any loan officer holds an active state license, which you can look up on NMLS Consumer Access. A licensed broker has to follow federal and state lending rules.
Key benefits of working with an independent broker include:
- Unbiased Product Access: Rather than forcing your budget into a single bank's fixed box, an independent advisor evaluates loans across multiple wholesale lenders, specialized lenders, and regional credit unions.
- Customized Deal Matching: If you have a unique financial profile, an independent broker can find lenders specializing in non-traditional scenarios.
- Transparent Fee Structures: Professional brokers explain all broker fees, administrative charges, and lender procurement fees upfront so there are no unexpected surprises at closing.
- Client Satisfaction Records: You can review past customer experiences and service track records on our Reviews page to see how personalized advice makes a difference.
Direct Bank Advising vs. Panel Mortgage Specialists
Why not just walk into your local bank branch where you hold your checking account? While direct bank advising seems convenient, it comes with inherent structural limitations.
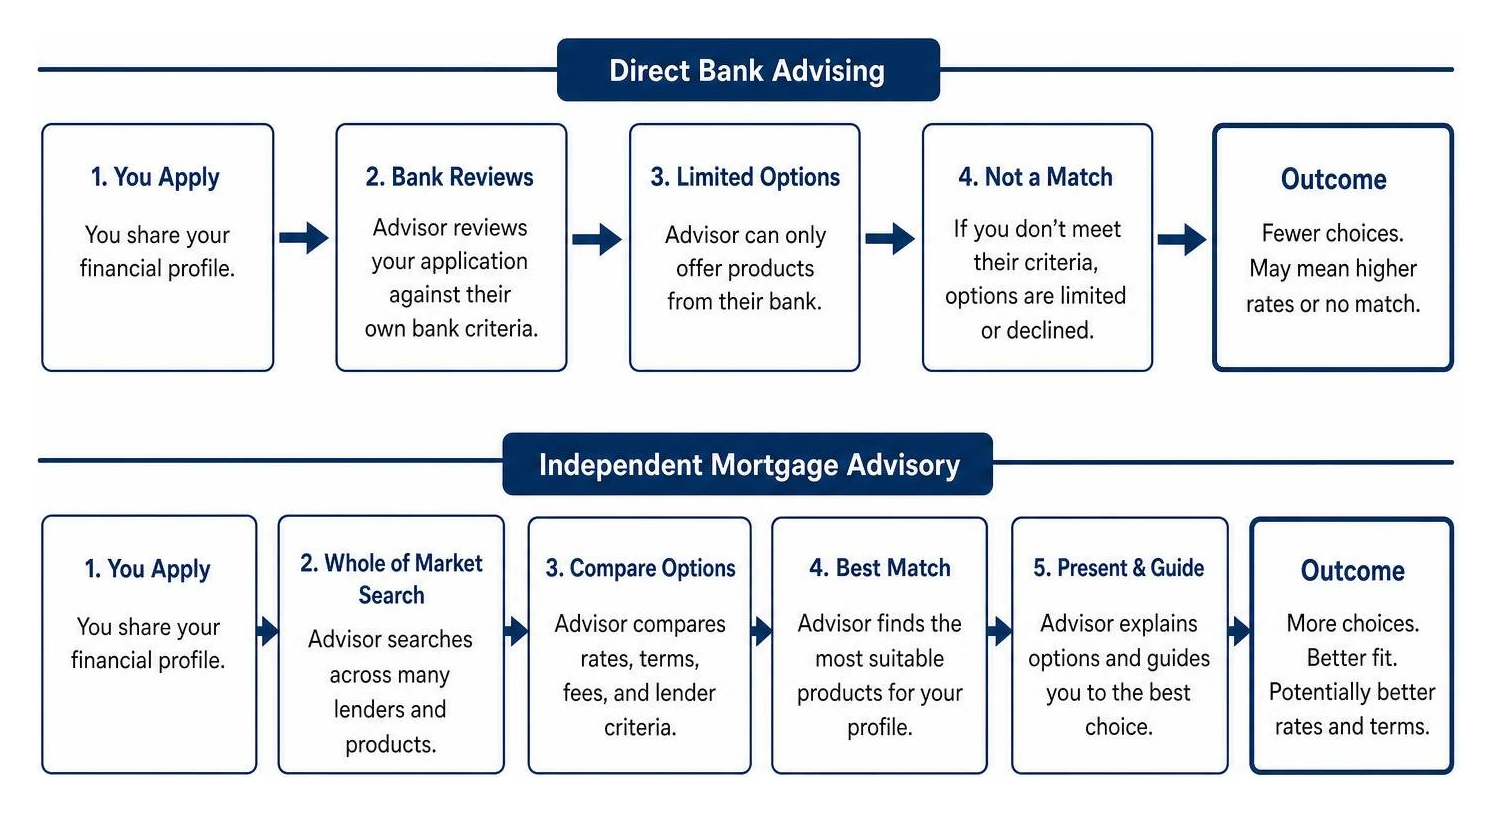
Direct bank advisors can only recommend products sitting on their immediate employer's shelf. If their bank requires a 700 credit score for a particular loan tier and your score is 675, that loan officer must simply decline your application or offer a significantly higher rate. They cannot redirect your file to a competing bank down the street that actively welcomes 675 credit scores with competitive rates.
Similarly, panel mortgage specialists are restricted to a closed list of partner institutions. While better than a single lender, panel advisors can miss competitive rates or flexible underwriting terms offered by lenders outside their panel. To understand how to evaluate loan representatives and pick the ideal professional for your scenario, review our guide on How to Find the Right Loan Officer.
The Step-by-Step Homebuying and Financing Process

Securing a mortgage does not have to feel like an overwhelming mystery. When you partner with a dedicated mortgage advisory service, the process breaks down into clear, manageable steps.
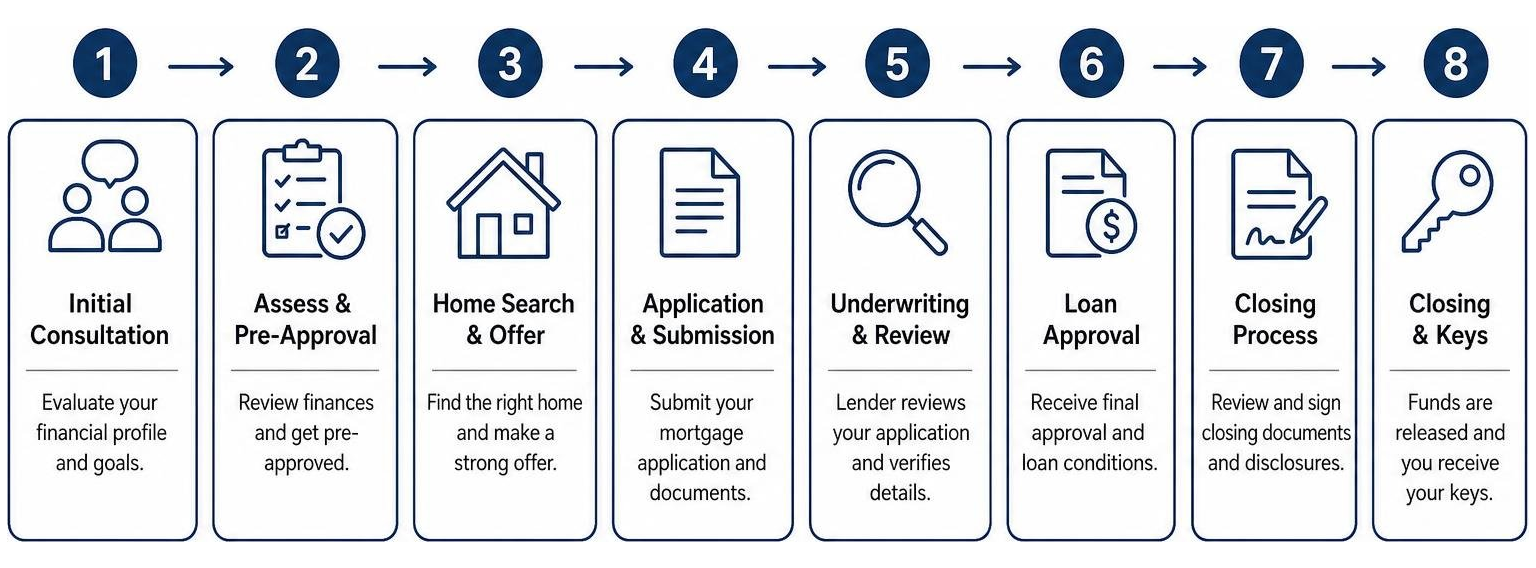
To help you visualize the timeline, the table below outlines each key milestone in the home financing process:
| Mortgage Process Milestone | Core Objective | Primary Deliverable / Outcome |
|---|---|---|
| 1. Initial Consultation | Evaluate income, debts, assets, and homebuying goals. | Actionable purchase budget and deposit target. |
| 2. Pre-Approval / AIP | Verify credit scores and financial paperwork. | Formal Pre-Approval Letter / Agreement in Principle. |
| 3. Property Search & Offer | Find a property and submit a purchase offer. | Executed Purchase & Sale Contract. |
| 4. Underwriting & Valuation | Lender conducts property appraisal and deep-dive financial audit. | Conditional Loan Approval & Clearance of Conditions. |
| 5. Closing & Key Handover | Review final Closing Disclosure, sign documents, and transfer funds. | Formal Loan Commitment, Deed Transfer, and Keys in Hand! |
To master each step before you start shopping, check out our interactive step-by-step Tutorial.
Consultation, Deposit Planning, and Pre-Approval
The home financing process begins long before you attend your first open house. During your initial consultation, your advisor conducts a complete budget analysis to establish your true purchasing power.
This phase includes evaluating:
- Deposit Requirements: Establishing how much cash you need for a down payment (this depends on the loan program, and some government programs need little or nothing down).
- Credit Score Verification: Reviewing your credit reports to identify any errors or quick-fix credit repair opportunities.
- Agreement in Principle (AIP) / Pre-Approval: Obtaining an official pre-approval document proving to real estate agents and sellers that you are a qualified buyer with vetted financing.
Start calculating your target numbers today with our online Pre Approval application and run custom monthly payment scenarios using our interactive Mortgage Calculator.
Submitting Offers, Underwriting, and Closing
Once you find the ideal property and submit an offer, your advisory service guides you through the technical stages of loan processing and underwriting:
- Property Valuation & Assessment: The lender orders an independent appraisal to verify that the home's market value supports the requested loan amount and that the property structure meets safety standards.
- Conveyancing and Title Review: Legal representatives conduct title searches to guarantee the property is free of legal liens or ownership disputes.
- Interest Rate Locking: Your advisor monitors market movements to help you execute a rate lock at the optimal moment. Read our strategy breakdown on When to Lock Your Mortgage Interest Rate to protect yourself against rate spikes.
- Final Closing & Loan Commitment: You review your final Closing Disclosure (CD) line-by-line, verify closing costs, transfer your remaining down payment funds, and sign final mortgage documents to receive your keys. Learn how to craft winning property bids with our guide on Submitting an Offer.
When Your Income or Property Is Complicated
Bank automated systems are built for simple W-2 files. If you own a business, earn commission, or are buying an unusual property, a broker can look at other lenders and other ways to structure the loan. If your file is complicated, tell me early. Most problems have a solution when we plan ahead.
If you have encountered hurdles during initial automated pre-assessments, explore our advice on overcoming obstacles with Trouble Getting Pre-Approved and review credit score threshold benchmarks in What Credit Score Do You Need for a Mortgage.
Mortgage Options for Bad Credit and Niche Loan Structures
Having past credit hiccups, aiming to buy a non-standard property (such as high-rise flats or rural acreage), or entering the market with a smaller deposit does not close the door on homeownership. Specialized loan products exist for virtually every scenario:
- Government-Backed Programs: Low down payment options including FHA Home Loans for flexible credit requirements, VA Home Loans for eligible military borrowers, and USDA Home Loans for eligible rural properties.
- Conventional Financing: Flexible fixed and variable options via Conventional Home Loans, structured over predictable terms like a 30-Year Fixed Mortgage or a budget-accelerating 15-Year Fixed Mortgage.
- High-Value Properties: Financing luxury homes exceeding standard conforming limits using Jumbo Home Loans.
- Flexible Terms & Niche Solutions: Capitalize on changing market cycles with an Adjustable Rate Mortgage, access cash equity in retirement through a Reverse Mortgage, bridge funding gaps using Down Payment Assistance Programs, or finance property renovations with a specialized Rehab Loan.
If you are weighing local market conditions and wondering whether now is the right moment to purchase, read our regional analysis on Should You Wait to Buy a Home in Florida.
Consumer Rights, Foreclosure Prevention, and Protection Services
Your relationship with a full-service mortgage advisory service does not end when you pick up your keys. Ongoing advisory support helps protect your investment, lower your ongoing housing expenses, and assist you if unexpected financial difficulties arise.
How a Professional Mortgage Advisory Service Protects Homeowners
Understanding your legal rights as a borrower is crucial for long-term home security:
- Foreclosure Prevention & Loss Mitigation: If you experience financial hardship, federal regulations and servicer protocols require lenders to explore loss mitigation before pursuing foreclosure. Connecting with a HUD-approved housing counselor or your advisory team provides free, independent guidance to negotiate payment plans or loan modifications.
- Scam Avoidance: Independent advisors help you verify genuine wire instructions and lender communications, shielding you from third-party closing scams and deceptive refinance schemes.
- Escrow & Rate Balance Monitoring: Servicers periodically adjust escrow collections due to property tax or insurance updates. Your advisor can explain monthly payment changes caused by adjustable-rate adjustments or escrow re-evaluations.
- PMI Removal Rules: Private Mortgage Insurance (PMI) protects the lender when you buy with less than 20% down. Once you build sufficient equity, federal regulations allow you to request formal PMI cancellation. Learn how to eliminate this extra fee in our deep dive on What is PMI Mortgage Insurance.
If consumer disputes arise with a mortgage servicer that cannot be resolved directly, you can file a complaint with the Consumer Financial Protection Bureau (CFPB), and the company is expected to respond. Federal compliance standards expect financial institutions to respond to CFPB complaints within 15 days.
Additionally, as interest rates drop over time, your advisor can help you evaluate a tax-smart loan replacement strategy through our Refinance portal.
Working With Your Financial Planner
I coordinate with your financial planner so the mortgage fits your cash flow, your savings goals, and your long term net worth.
Frequently Asked Questions about Mortgage Advisory Services
What is an independent mortgage broker and how do they differ from direct lenders?
A bank loan officer can only offer that bank's loans. An independent broker can compare loans from multiple wholesale lenders and match your scenario to the one whose guidelines and pricing fit best.
What should you do if you are struggling to make your monthly mortgage payments?
If you encounter financial difficulty, take action immediately:
- Contact your mortgage servicer right away to discuss loss mitigation, forbearance options, or loan modification plans.
- Reach out to a HUD-approved housing counselor for independent, free assistance in structuring a repayment strategy.
- If your servicer fails to follow regulatory guidelines or mismanages your account, submit a formal complaint through the Consumer Financial Protection Bureau (CFPB), which requires servicer responses within 15 days.
Can a broker help if my income is complicated?
Often, yes. If you own a business or earn commission, your tax returns may not show your full income. I look at the complete picture and find a lender whose guidelines fit.
Conclusion
Finding the right mortgage isn't just about securing an interest rate; it's about building a solid foundation for your financial future. At Home Loan Advisors LLC, based in Tampa, Florida, we believe every homebuyer deserves transparent, education-driven guidance every step of the way.
Whether you are buying your very first home, refinancing an existing property, or working through a complex loan scenario, I combine fast quotes with personal guidance.
Ready to take the next step toward your homeownership goals? Visit Home Loan Advisors, explore our tools to Buy a Home, or Get a Quote today. Have questions? Reach out directly via our Contact page to speak with a dedicated specialist who is ready to walk you through your options.