Connect with top rated mortgage loan brokers near me today
When you begin searching for mortgage loan brokers near me, it helps to understand how a mortgage broker actually operates compared to a traditional retail bank or direct lender.
A direct bank or retail lender only sells its own proprietary home loan products. If their specific underwriting guidelines, interest rates, or down payment requirements do not fit your financial profile, the loan officer at that bank has no choice but to decline your application or offer a suboptimal rate.
In contrast, an independent mortgage broker acts as a professional intermediary between you and a vast network of wholesale lenders. Mortgage brokers typically partner with anywhere from 10 to 30 or more wholesale lenders. This setup allows them to shop wholesale interest rates on your behalf.
According to a report by the Mortgage Bankers Association, mortgage brokers originate roughly 68% of all residential mortgage loans in the United States. This high adoption rate is largely driven by access to competitive pricing and diverse loan structures. Research from LendingTree indicates that borrowers who work with a mortgage broker save an average of $1,200 in closing costs compared to those who go directly to a bank.
| Feature | Direct Bank / Retail Lender | Mortgage Broker |
|---|---|---|
| Product Selection | Offers only internal loan products | Accesses 10 to 30+ wholesale lenders |
| Pricing Model | Retail rates set by internal department | Wholesale rates competitive across multiple sources |
| Underwriting Flexibility | Rigid, single-lender criteria | Flexible matching with niche underwriting guidelines |
| Primary Loyalty | Represents the bank | Serves as an independent advisor to the buyer |
| Shopping Process | You must re-apply at every individual bank | Single application applied across multiple lenders |
Benefits of Working with Mortgage Loan Brokers Near Me
Choosing a local professional offers significant advantages over using distant, impersonal online portals.
First, local mortgage brokers bring deep regional housing market insight. They understand local tax rates, regional insurance nuances, state-specific down payment assistance programs, and localized appraisal dynamics. When real estate agents present purchase offers to sellers, a pre-approval letter from a respected local professional often carries far more weight than one generated by an automated online generator.
Second, a local broker offers personalized, education-focused guidance. Instead of forcing you into a standard product, we take the time to evaluate your unique income, credit score, and long-term financial goals. If you want to dive deeper into selecting the right specialist for your situation, read our comprehensive guide on How to Find the Right Loan Officer.
How to Find and Choose Mortgage Loan Brokers Near Me
Finding the right broker requires thorough vetting to protect your finances and ensure a smooth transaction. As of 2023, there are approximately 86,000 licensed mortgage loan originators operating across more than 20,000 brokerages nationwide. With so many options available, systematic evaluation is key.
Start by verifying every candidate's license using the NMLS Consumer Access database. This free public directory allows you to check state licenses, authority status, employment history, and any regulatory actions or legal disclosures.
Next, audit public client feedback across unbiased review platforms. Pay attention to how the firm handles complex scenarios, meets closing deadlines, and communicates throughout underwriting. You can see real feedback from families we have guided by visiting our verified Reviews page.
Watch out for these common warning signs when speaking with potential originators:
- Upfront fee demands: Brokers should never charge high out-of-pocket setup fees before work begins.
- Guaranteed low rates without documentation: Accurate pricing requires reviewing credit files and income assets.
- Pressure tactics: A good broker empowers you through education rather than rushing your decision.
- Vague fee disclosures: Compensation structures should always be fully transparent.
Questions to Ask Mortgage Loan Brokers Near Me Before Hiring
Before signing agreements or submitting documents, conduct a brief interview. Here are key questions to ask:
- "How many wholesale lenders do you regularly work with?"(Look for brokers connected to at least 10–15 quality wholesale partners).
- "How are your fees structured, and who pays them?"(Ensure full disclosure on lender-paid versus borrower-paid options).
- "What are your current turn times for processing and underwriting?"(Make sure their timeline aligns with your purchase contract deadlines).
- "How do you handle the pre-approval phase?"(A true pre-approval involves verified income and credit, not just an unverified pre-qualification).
To start your process with verified financial figures, you can easily initiate a fully documented Pre Approval through our team.
Matching Loan Products to Your Financial Needs
No two financial situations are identical. Whether you receive W-2 income, run a small business, have higher credit card balances, or possess non-traditional asset structures, an independent broker matches your profile to the right lending program.
Brokers evaluate your Debt-to-Income (DTI) ratio, Loan-to-Value (LTV) ratio, income history, and credit profile to select wholesale lenders offering favorable terms for your specific situation.
Conventional, Government, and Niche Loan Options
Here is a overview of the main loan options we utilize for borrowers:
- Conventional Loans: Ideal for buyers with strong credit scores (620+) and stable cash reserves. To learn about competitive rates and down payment options starting as low as 3%, explore our Conventional Home Loans.
- FHA Loans: Backed by the Federal Housing Administration, these programs are well-suited for buyers with modest credit or lower down payments. Find out more by visiting our FHA Home Loans section.
- VA Loans: Designed exclusively for active military personnel, veterans, and surviving spouses, offering zero down payment options and no monthly mortgage insurance. Review military benefits on our VA Home Loans page.
- USDA Loans: Intended for eligible rural and suburban properties, providing 100% financing for qualifying lower-to-moderate-income buyers. Check geographic eligibility with our USDA Home Loans guidelines.
- Jumbo Loans: Tailored for higher-value luxury properties that exceed standard conforming loan limits. Explore custom jumbo financing solutions under our Jumbo Home Loans program.
Understanding Broker Compensation, Documents, and Timelines
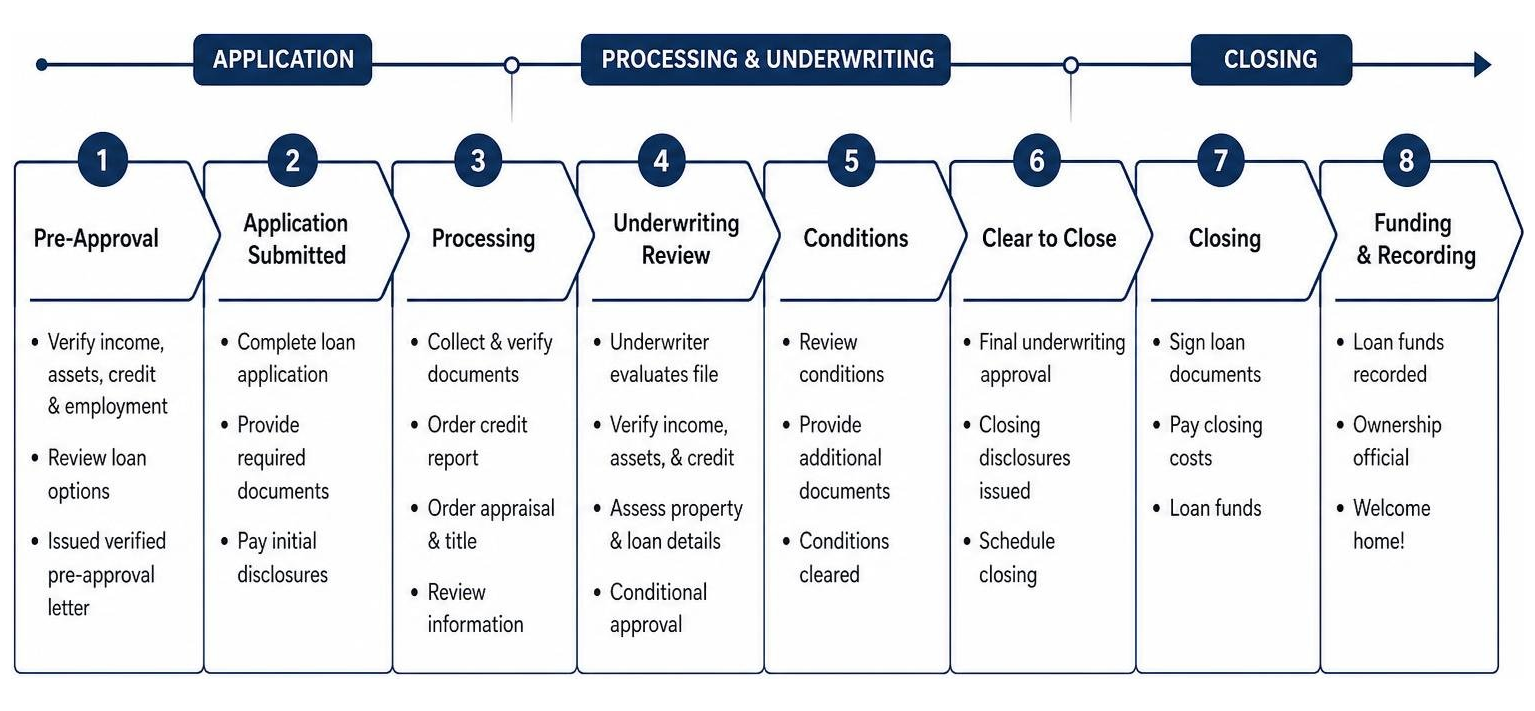
Understanding broker compensation helps you evaluate quotes with confidence. Brokers typically earn between 1% and 2% of the total loan amount. Federal regulations strictly prohibit mortgage brokers from charging dual compensation; they are paid either via Lender-Paid Compensation(where the wholesale bank pays the broker fee without added costs to you) or Borrower-Paid Compensation(where the fee is included in your closing expenses).
When evaluating options, request a formal Loan Estimate (LE) form within three business days of submitting your application. This standardized document outlines your interest rate, monthly payment, closing costs, and cash-to-close requirements, making it easy to compare offers.

To keep your application moving quickly, gather these core documents in advance:
- Income Documentation: Recent pay stubs (30 days) and W-2 statements (past 2 years).
- Tax Records: Signed personal and business federal tax returns (past 2 years).
- Asset Verification: Full bank account statements (past 2-3 months) showing sufficient funds for closing.
- Identification: State driver's license or passport.
- Self-Employed Records: Year-to-date Profit & Loss statement and balance sheet (if applicable).
The loan process typically takes 30 to 45 days from initial application to final funding.
To see exact terms and rate options personalized for your scenario, request a fast, accurate Get a Quote from our originators today.
Frequently Asked Questions About Local Mortgage Brokers
How much do mortgage brokers charge for their services?
In most residential mortgage transactions, the broker is compensated by the wholesale lender that funds the loan. This lender-paid compensation model means you typically pay zero direct out-of-pocket fees to the broker for their service. Any fees paid directly by the borrower must be explicitly disclosed on your standard Loan Estimate document.
What documents are required to apply through a local broker?
Standard documentation includes tax returns (2 years), W-2 forms (2 years), recent pay stubs covering the last 30 days, bank account statements for the last 60–90 days, government-issued photo identification, and documentation of any supplemental income or assets.
How do I compare quotes from multiple brokers?
To compare quotes accurately, review Section A (Origination Charges) and Section B (Services You Cannot Shop For) on Page 2 of the official Loan Estimate forms provided by each broker. Compare the Annual Percentage Rate (APR) rather than just the nominal interest rate, as the APR reflects the total loan cost including fees over time.
Conclusion
Finding trusted mortgage loan brokers near me does not have to be stressful. By focusing on educational guidance, market access, transparent fee structures, and verified credentials, you can navigate your mortgage with total confidence.
At Home Loan Advisors LLC, we combine custom financial strategies with dedicated local support to guide you through every step of the mortgage process—from initial pre-approval all the way to key exchange.
Ready to discover your best home financing options? Visit Home Loan Advisors to get started, or reach out to our team directly through our Contact page today.