Florida Mortgage Rates 2026 and What Tampa Buyers Should Expect
Understanding Tampa mortgage rates today starts with two things: the broader national bond market and the local Tampa Bay housing picture. Rates can move daily, and the number you see quoted online may not match the number available for your credit profile, property type, loan program, down payment, and whether the home is in Tampa, St. Petersburg, Clearwater, Brandon, Wesley Chapel, Riverview, or another nearby community.
Tampa Bay still draws steady buyer interest because of its employment base, airport access, medical and university systems, port activity, and lifestyle demand across Hillsborough, Pinellas, and Pasco counties. But the right mortgage strategy depends on the full file, not a headline rate.
When comparing Tampa mortgage rates today, buyers often review three core loan structures:
- 30-Year Fixed Mortgage : Built for payment stability because the principal and interest portion is fixed for the loan term.
- 15-Year Fixed Mortgage : May help borrowers pay down principal faster, but the monthly payment is usually higher than a longer-term option.
- Adjustable Rate Mortgage : Starts with a fixed introductory period before later adjustments. This may be worth exploring for some buyers, depending on plans, budget, and risk tolerance.
Comparing Loan Options Under Tampa Mortgage Rates Today
Loan type can affect pricing, required documentation, mortgage insurance, property standards, and cash needed to close. Josh can help you compare options without assuming one program is right for your situation.
- Conventional Home Loans : Often used by borrowers with established credit and income documentation. Mortgage insurance may apply depending on the file.
- FHA Home Loans : An FHA-insured loan option may be worth reviewing for buyers who want flexible credit and down payment guidelines. This content is not from, endorsed by, or approved by the Federal Housing Administration.
- VA Home Loans : Eligible service members, veterans, and surviving spouses may be able to explore VA loan options. This content is not from, endorsed by, or approved by the U.S. Department of Veterans Affairs.
- USDA Home Loans : USDA-related financing may be available in certain eligible areas outside the urban core. This content is not from, endorsed by, or approved by the U.S. Department of Agriculture.
- Jumbo Home Loans : Used for higher-priced properties that exceed conforming loan limits, often with more detailed credit, asset, and reserve review.
Compliance review flag: this section mentions Conventional, FHA, VA, USDA, and Jumbo loan programs. Eligibility language, disclosures, and any required NMLS placement should be reviewed before publication.
Monthly Payment Breakdown: PITI for Tampa Bay Homes
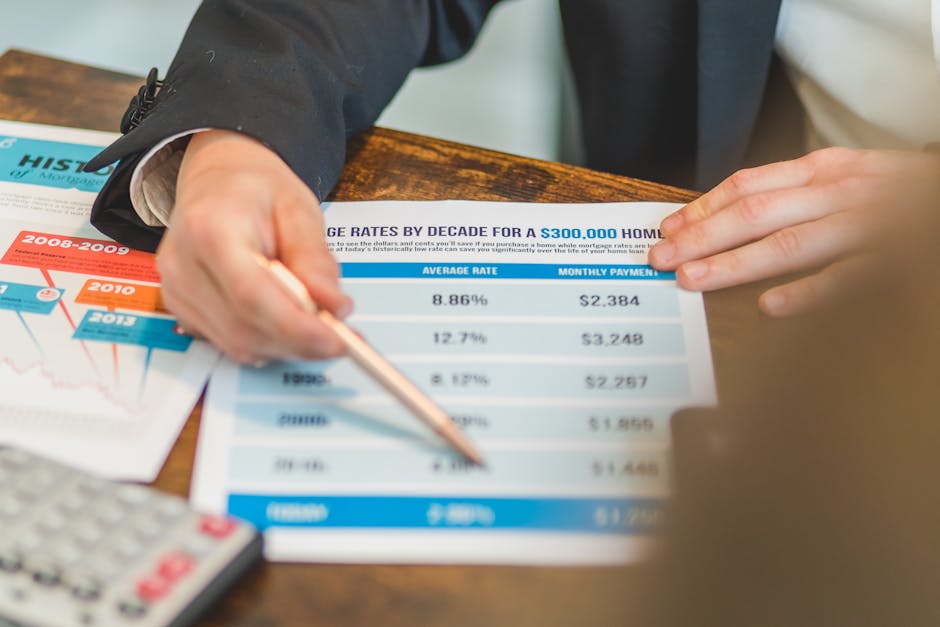
A mortgage payment is more than principal and interest. In Tampa Bay, your real monthly housing cost usually comes down to PITI: Principal, Interest, Taxes, and Insurance.
Here is what to review before you compare homes in Tampa, St. Petersburg, Clearwater, or nearby communities:
- Principal and Interest (P&I): This is based on your loan amount, rate, and term. Two buyers looking at the same purchase price can still have different payments because their loan files are different.
- Property Taxes: Florida property taxes vary by county, city, exemptions, assessed value, and whether the property qualifies as a primary residence. Hillsborough, Pinellas, and Pasco County tax estimates can look different even when purchase prices are similar.
- Homeowners Insurance: Florida insurance costs can be a major part of the payment. Wind, flood, roof age, property location, and carrier guidelines can all matter.
- Mortgage Insurance: Some loan structures include mortgage insurance or similar charges depending on the program, down payment, and equity position.
To test custom scenarios based on your specific target purchase price, check out the Mortgage Calculator or explore local data models via Mortgage Payment Tampa 2026 | CalcFi. For details on how mortgage insurance can affect your bill, read our overview on What is PMI Mortgage Insurance?.
How Down Payments May Impact Monthly Expenses at Tampa Mortgage Rates Today
The amount you put down can change the loan amount, monthly payment, interest paid over time, and whether mortgage insurance applies. But there is not one down payment strategy that fits every buyer.
For example, a larger down payment may reduce the loan balance and could lower the monthly payment. A smaller down payment may help preserve cash for moving costs, repairs, reserves, or insurance deductibles. In Florida, that cash cushion can matter because homeownership costs may include items buyers do not always expect, like wind mitigation updates, flood insurance review, or roof-related insurance questions.
The clean way to compare is to run side-by-side estimates using the same property, same county, and same insurance assumptions.
Affordability Analysis: Income, Cost of Living, and Rent vs. Buy
Affordability in Tampa Bay depends on more than the purchase price. Your income, debts, credit profile, cash to close, property taxes, insurance, HOA dues, and commute all shape the real number.
A home in South Tampa may have a different tax and insurance profile than a condo in downtown St. Petersburg, a single-family home in Clearwater, or a property in Riverview or Wesley Chapel. That is why broad online estimates can be useful for orientation, but they should not be treated as a final budget.
When you review affordability, pay attention to:
- Total housing payment: Principal, interest, taxes, insurance, mortgage insurance if applicable, HOA dues, and flood insurance if required or chosen.
- Florida insurance considerations: Roof age, wind mitigation features, elevation, flood zone, and property condition can affect the monthly budget.
- Commute and transportation costs: Tampa Bay traffic patterns can change your monthly cash flow, especially if you cross bridges, commute between counties, or rely on paid parking.
- Reserves after closing: Keeping money available after closing may be just as important as reducing the loan balance.
The Rent vs. Buy Landscape in Tampa Bay
Renting can make sense if you need flexibility, are still learning the area, or do not want responsibility for repairs yet. Buying may make sense if you want stability, plan to stay long enough for ownership costs to make sense, and are comfortable with the ongoing responsibilities.
The better question is not simply “rent or buy?” It is: “What happens to my monthly budget if I buy this specific property in this specific part of Tampa Bay?”
For detailed analysis on market timing, read our article on whether you Should You Wait to Buy a Home in Florida?. Buyers who want to review possible help with upfront costs can also explore state and local options via Down Payment Assistance Programs, including programs that may be available through Florida or local housing agencies depending on eligibility and funding.
Steps to Compare Rates and Buy a Home in Tampa Bay
A stronger mortgage plan usually starts before you make an offer. Here is a practical way to prepare:
- Review Your Credit Early: Lenders price loans based on the full file, and credit is one part of that. Check for errors, reduce revolving balances where possible, and avoid taking on new debt before applying. Learn more in our guide: What Credit Score Do You Need for a Mortgage?.
- Organize Financial Documentation: Gather tax returns, W-2s, pay stubs, bank statements, and asset records. Clean documentation can make underwriting smoother.
- Request a Pre-Approval Review: A pre-approval can help clarify a working budget, but it is not final loan approval. Final approval depends on underwriting, property review, title, appraisal if required, and loan conditions. Start the process online with our Pre Approval portal. If you run into hurdles during this stage, check out Trouble Getting Pre-Approved? .
- Work With a Local Mortgage Professional: Tampa Bay files often involve Florida-specific questions around insurance, condos, flood zones, property taxes, and county-level differences. Learn how to connect with the right person in How to Find the Right Loan Officer .
- Discuss the Rate Lock Strategy: Rates can change based on market conditions. Once you are under contract, talk through whether locking or floating makes sense for your situation. Read more in When to Lock Your Mortgage Interest Rate .
Frequently Asked Questions About Tampa Mortgage Rates
Can a household earning a local median income afford a median-priced home in Tampa Bay?
It depends on the full file. Income is only one part of the answer. Debt, credit, down payment, property taxes, insurance, HOA dues, reserves, and the specific home all matter. A buyer looking in Tampa may have a different budget than a buyer comparing St. Petersburg, Clearwater, Brandon, or Wesley Chapel because taxes, insurance, and HOA costs can vary.
Is it better to rent or buy in Tampa given current market conditions?
There is not a single answer that fits every household. Renting may be the better fit if you want flexibility or are still deciding where in Tampa Bay you want to live. Buying may be worth exploring if you plan to stay, have stable income, understand the full monthly cost, and want the possibility of building equity over time.
What down payment assistance programs are available for Tampa homebuyers?
Tampa Bay buyers may be able to explore state, county, or local housing assistance programs depending on eligibility, funding availability, property location, and loan structure. Examples may include Florida housing programs, local Housing Finance Authority options, or employer-related assistance where available.
Program rules can change, so it is better to review the current guidelines before writing an offer. Compliance review flag: assistance program and loan eligibility language should be reviewed before publication.
Next Steps for Tampa Bay Homebuyers
Navigating Tampa mortgage rates today means looking at the whole picture: rate, loan structure, property taxes, Florida insurance, mortgage insurance, reserves, and how long you expect to own the home.
Josh Jampedro is a Tampa, Florida mortgage broker and vice president with more than 1,000 closed transactions and more than 10 years of experience. Through Home Loan Advisors LLC, the goal is to help you understand your options clearly, not push you into a loan that does not fit.
If you want to talk through what may make sense for your situation:
- Start a purchase conversation: Buy a Home
- Review whether refinancing is worth discussing: Refinance
- Request personalized information for your scenario: Get a Quote
Official Josh Jampedro platforms: Instagram @joshjampedro, YouTube @BetterRate, LinkedIn linkedin.com/in/josh-jampedro, Facebook FLHomeLoanAdvisors, and website joshjampedro.com.
Mortgages are complex so let me give you the tools you need to make the right decisions.