Use a Tampa Mortgage Calculator to Plan Your Buying Power
Estimate Your Tampa Mortgage Payment Before You Shop
A Tampa mortgage calculator helps you estimate the full monthly cost of buying a home, not just the loan payment. That matters across Tampa Bay, whether you are looking in Tampa, St. Petersburg, Clearwater, Brandon, Riverview, Wesley Chapel, or nearby communities.
| Input | Tampa Bay planning item |
|---|---|
| Home price | Use the price range you are considering |
| Down payment | Enter the amount you plan to contribute |
| Interest rate | Use a current quote for your profile and loan scenario |
| Monthly housing cost | Estimate principal, interest, taxes, insurance, and any HOA or flood-related costs |
| Rent comparison | Compare against your actual lease cost and expected rent changes |
PITI means principal, interest, property taxes, and homeowners insurance. In Tampa Bay, those last two items can make a big difference. Florida property taxes, homeowners insurance, wind coverage, flood-zone considerations, HOA dues, and community fees can change the monthly estimate from one property to the next.
A calculator gives you a useful starting point. But your real payment will depend on the home price, down payment, credit profile, loan type, insurance quote, tax assessment, and any HOA or flood-insurance costs. This guide will help you use Tampa Bay-specific inputs to set a realistic buying budget before you make an offer.
How Tampa Housing Market Economics Affect Affordability
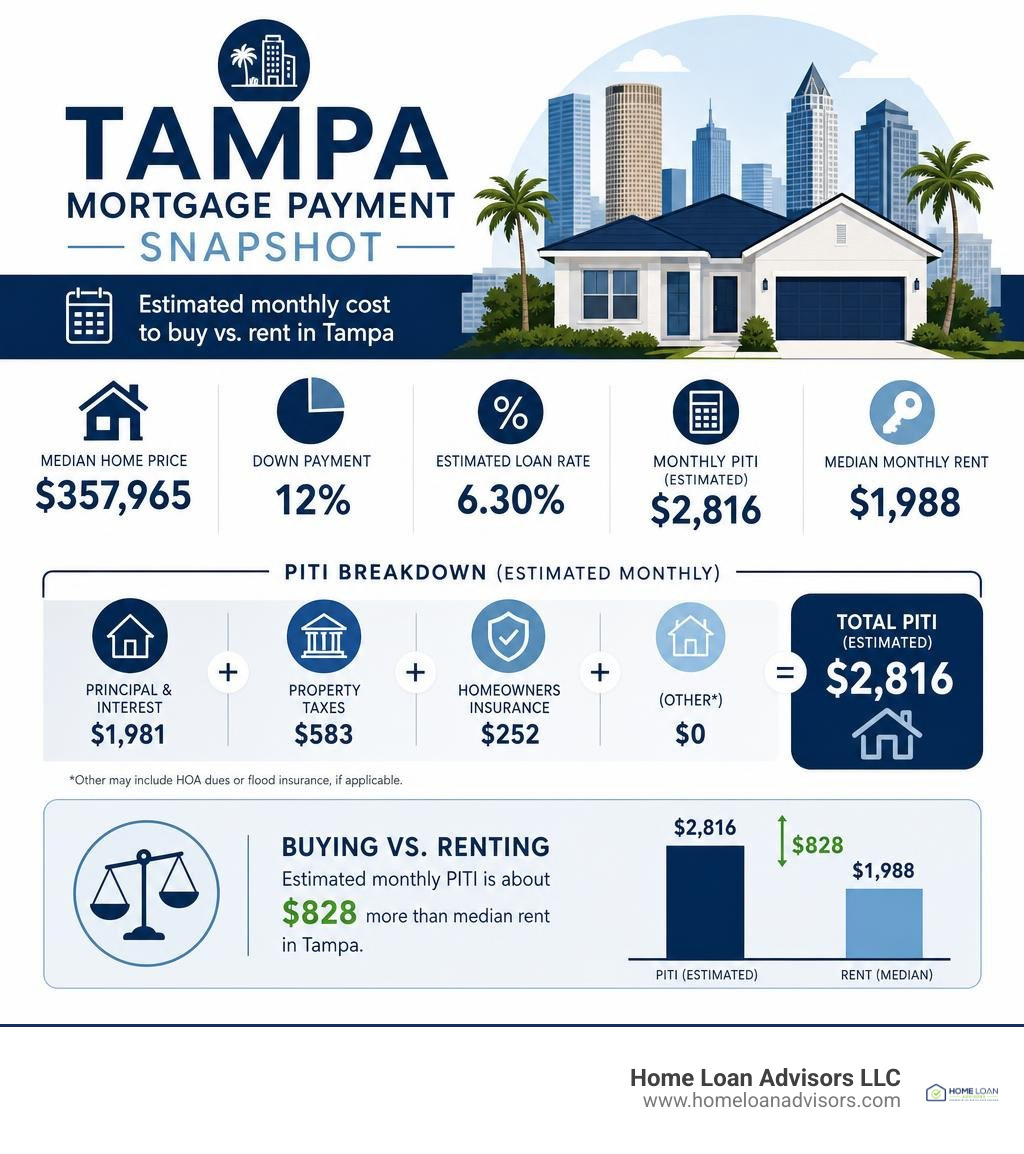
Understanding local market economics is essential when you evaluate what you can afford in Tampa Bay. A budget based on national rules of thumb can miss Florida-specific costs, especially insurance, taxes after a sale, flood-zone considerations, and HOA or condo fees.
When analyzing the local market, several factors can shape overall housing affordability:
- Income vs. housing costs: Compare your gross monthly income, recurring debts, and savings against the full housing payment, not just principal and interest.
- Rent vs. buy pressure: Rent may have a lower initial monthly cost in some cases, but buying may offer long-term stability if the full cost fits your budget.
- Florida cost factors: Homeowners insurance, wind exposure, flood-zone status, and condo or HOA requirements can vary across Tampa, St. Petersburg, Clearwater, and surrounding communities.
- Commute and lifestyle costs: A property in South Tampa, Westchase, Seminole Heights, Brandon, Riverview, or Pinellas County may change your transportation costs, toll use, parking, and daily budget.
Estimating Monthly PITI with a Tampa Mortgage Calculator
To estimate your true housing expenses, a basic loan calculation is not enough. You need to calculate PITI: Principal, Interest, Taxes, and Insurance.
Start with the home price you are considering, subtract your planned down payment, and use a current rate quote tied to your actual profile and loan scenario. Then add property taxes, homeowners insurance, mortgage insurance when applicable, HOA dues, condo fees, CDD fees, and any flood-insurance estimates.
You can test your own figures with our custom Mortgage Calculator or compare general city-level models using tools like the Mortgage Payment Tampa 2026 | CalcFi tool.
Renting vs. Buying in Hillsborough County
Deciding whether to buy a home or sign another lease in Hillsborough County requires looking beyond the first monthly payment.
| Metric | Renting | Buying |
|---|---|---|
| Monthly out-of-pocket | Based on your lease and renewal terms | Based on full PITI, HOA, flood, and property-specific costs |
| Flexibility | Easier to move at lease end | More planning needed before selling or refinancing |
| Wealth-building potential | No ownership equity | Possible equity growth, depending on market and loan payoff |
| Payment stability | Rent can change at renewal | Principal and interest may be stable with a fixed-rate loan, while taxes and insurance can change |
Renting may make sense when you need flexibility or when the full cost of ownership would stretch your budget. Buying may make sense when the payment, cash reserves, and time horizon fit your situation. The right answer depends on the property and your numbers.
Breaking Down PITI: Taxes, Insurance, and PMI in Florida
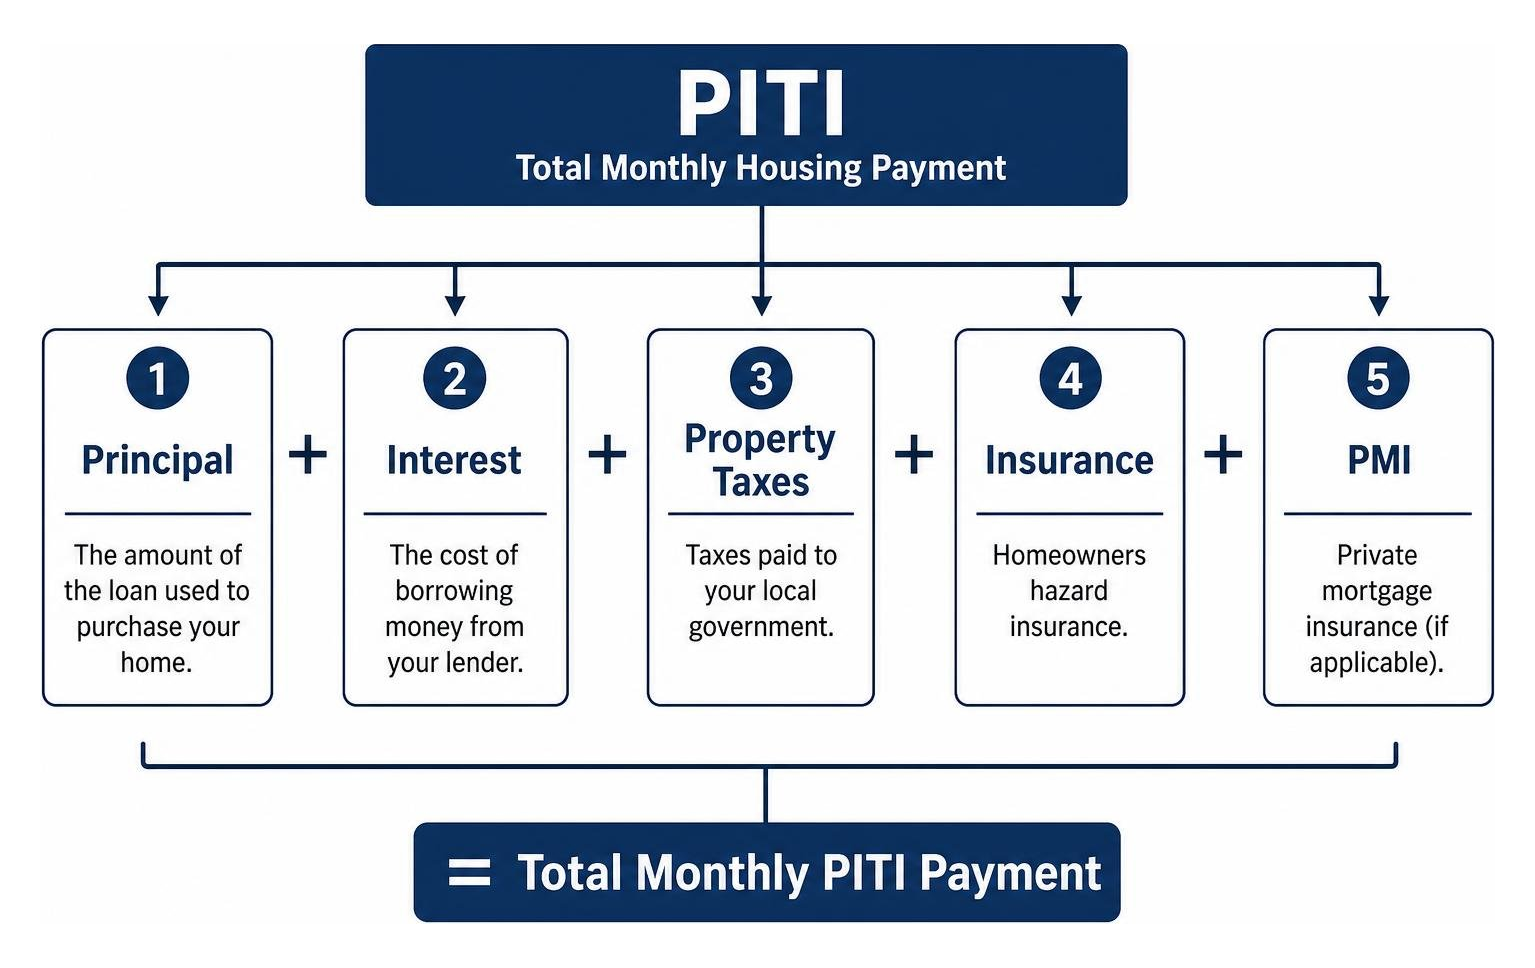
When running numbers on a Tampa mortgage calculator, understanding how escrow items are calculated under Florida state law keeps your budget more realistic.
Florida Property Taxes and Hillsborough Millage Rates
Property taxes in Tampa Bay depend on the purchase price, assessed value, exemptions, local millage rates, and whether the home will be your primary residence. The seller's current tax bill may not match what you pay after the property changes hands.
If you make the home your primary residence, Florida Homestead Exemption rules may reduce taxable value, and the Save Our Homes assessment cap may affect future assessed-value increases. The details depend on the property, timing, and local tax rules, so it is smart to review the Hillsborough County property appraiser estimate or the applicable county office if you are looking outside Tampa, such as Pinellas or Pasco County.
Impact of Homeowners Insurance and PMI Costs
Homeowners insurance is a major factor in Florida housing costs. Tampa Bay buyers may need to consider windstorm coverage, roof age, property condition, flood-zone status, and the insurer's underwriting requirements. A real insurance quote is more useful than a national calculator default.
Additionally, putting down less than the threshold required to avoid mortgage insurance may add PMI or another form of mortgage insurance, depending on the loan program. To explore how down payment variations may affect these costs, check out our guide on What is PMI Mortgage Insurance and see how loan structure affects long-term amortized debt with a 30-Year Fixed Mortgage.
Understanding Local Inputs for a Tampa Mortgage Calculator
Standard online calculators can underestimate local taxes, Florida insurance costs, and property-specific fees.
Localizing Property Tax and Insurance Estimates
To evaluate your potential payment more accurately, input local parameters rather than relying on national defaults:
- County and city tax inputs: Use the county tied to the property, such as Hillsborough, Pinellas, Pasco, or Manatee, and account for city-specific millage where applicable.
- Insurance quoting: Use real quotes when possible, especially for single-family homes, condos, older roofs, waterfront properties, or homes in flood-prone areas.
- HOA, condo, and CDD fees: These costs can reduce your available monthly budget and may affect loan review.
- Tax adjustments: Property taxes may reset based on your purchase price after the sale, so do not rely only on the seller's historic tax bill.
For additional math models tailored to local property parameters, you can reference resources like Daily Calcs' Tampa Mortgage Tool.
How to Use a Tampa Mortgage Calculator to Evaluate Loan Options
Adjusting variables on a Tampa mortgage calculator helps you compare possible loan structures:
- Comparing loan terms: A longer term may lower the monthly principal and interest payment, while a shorter term may reduce total interest paid over time if the payment fits your budget.
- Testing principal prepayments: Extra principal payments may reduce the payoff timeline and total interest, depending on the loan terms. You can analyze payoff acceleration math using tools like Extra Mortgage Payment Tampa 2026 | CalcFi.
- Loan strategy matching: Compare standard financing options by reviewing Conventional Home Loans to see which down payment and mortgage-insurance structure may fit your overall savings goals.
Qualification Rules and Down Payment Assistance in Tampa

Understanding what lenders review can make the mortgage process less confusing when you are preparing to make an offer in Tampa Bay.
Credit Score and Debt-to-Income Standards
Lenders evaluate two primary factors during mortgage underwriting: credit history and debt-to-income ratio.
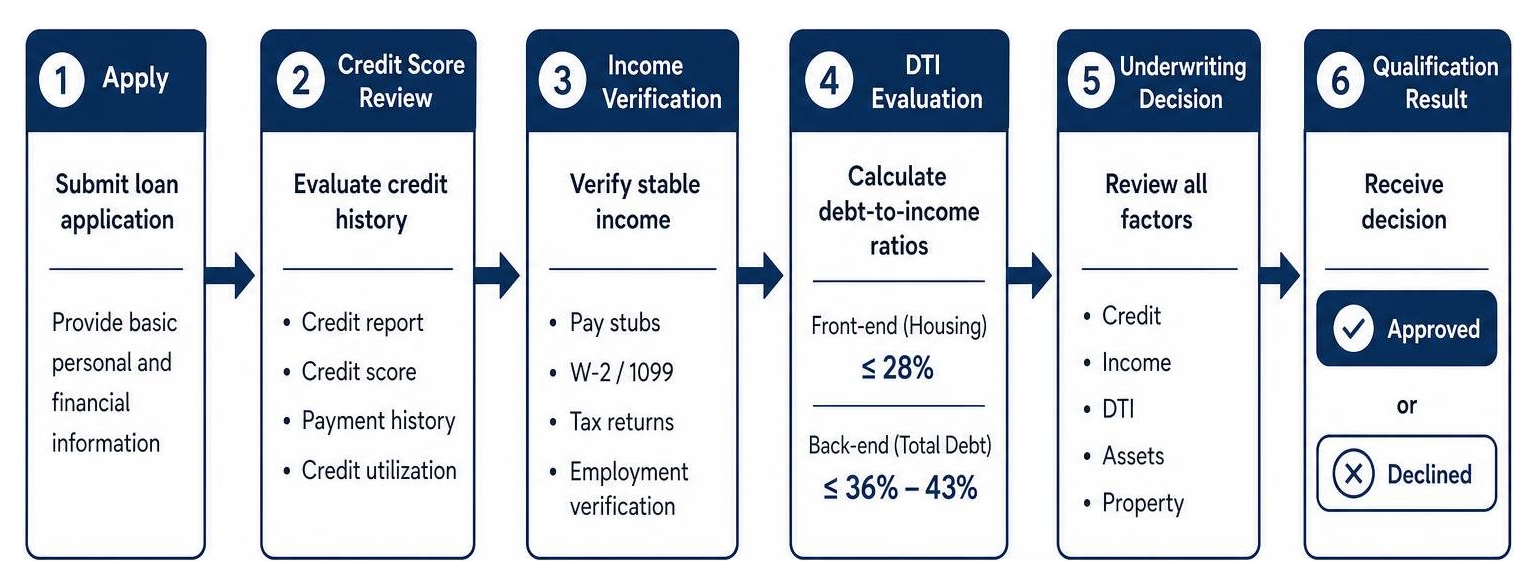
- Credit score review: Minimum credit score standards vary by loan program, lender, occupancy, property type, and full borrower profile. Learn more in our review on What Credit Score Do You Need for a Mortgage.
- DTI review: Lenders compare your housing payment and other monthly debts against your gross income. The acceptable range depends on the full file, including reserves, credit, loan type, and automated underwriting findings.
- Local qualification gap: In Tampa Bay, insurance, taxes, HOA dues, condo fees, and flood insurance may be the difference between a comfortable budget and a stretched one. Some buyers may explore loan options such as FHA Home Loans with Josh's help, or run broader budget estimates with the Mortgage Affordability Tampa 2026 | CalcFi calculator.
Pre-qualification and pre-approval are useful planning steps, but final approval depends on underwriting, documentation, property review, and loan-program requirements.
Local Down Payment Assistance Programs
If upfront cash is holding you back, local and state assistance programs may be worth exploring. Availability, funding, eligibility, income limits, property rules, and repayment terms can change.
- Dare to Own the Dream: A City of Tampa program that may help eligible buyers with down payment and closing cost assistance, subject to current program rules and funding.
- Tampa CRA DPA: Assistance that may apply in specific Community Redevelopment Areas across the City of Tampa, subject to current eligibility rules.
- Hometown Heroes & FL Assist: State-level options that may provide secondary financing assistance for eligible buyers, depending on current program guidelines.
Read complete details on eligibility rules via our dedicated overview of Down Payment Assistance Programs.
Frequently Asked Questions About Mortgages in Tampa
Can a household with a moderate income afford a median-priced home in Tampa?
It depends on the full payment, not just the home price. A Tampa Bay buyer should factor in principal, interest, taxes, homeowners insurance, mortgage insurance when applicable, HOA or condo dues, flood insurance, and cash reserves. If the full payment feels tight, options may include adjusting the price range, increasing savings, reviewing assistance programs, or comparing loan structures with a licensed mortgage professional.
How much is the average monthly property tax bill on a Tampa home?
The monthly property tax escrow depends on the purchase price, assessed value, exemptions, millage rate, and whether the home is in Hillsborough County, Pinellas County, Pasco County, or another nearby area. The seller's current tax bill may not be a reliable estimate after the home changes ownership, so use a property-specific estimate whenever possible.
Is it cheaper to rent or buy a home in Tampa?
Sometimes renting has a lower initial monthly outlay. Buying may make sense when the full payment, cash needed to close, reserves, and time horizon fit your situation. A Tampa mortgage calculator can help you compare both paths using your real rent, property price, insurance quote, taxes, and HOA costs.
Conclusion
Using a localized Tampa mortgage calculator gives you a clearer picture of what it may take to buy a home in Hillsborough County and across Tampa Bay. By accounting for Florida property taxes, homeowners insurance, HOA dues, condo fees, flood-zone considerations, and available program options, you can build a budget that fits the property and your situation.
Josh Jampedro is a Tampa, Florida mortgage broker and vice president with more than 1,000 closed transactions and more than 10 years of experience. His official platforms are Instagram @joshjampedro, YouTube @BetterRate, LinkedIn linkedin.com/in/josh-jampedro, Facebook FLHomeLoanAdvisors, and website joshjampedro.com.
If you want help reviewing your numbers, you can start a conversation through Pre Approval or Get a Quote. Pre-approval is not final loan approval; final approval depends on underwriting, documentation, property review, and program requirements.
Mortgages are complex so let me give you the tools you need to make the right decisions.